New data from Brand Finance reveals more than half of luxury brands continue to grow in value despite weakness across traditional luxury categories
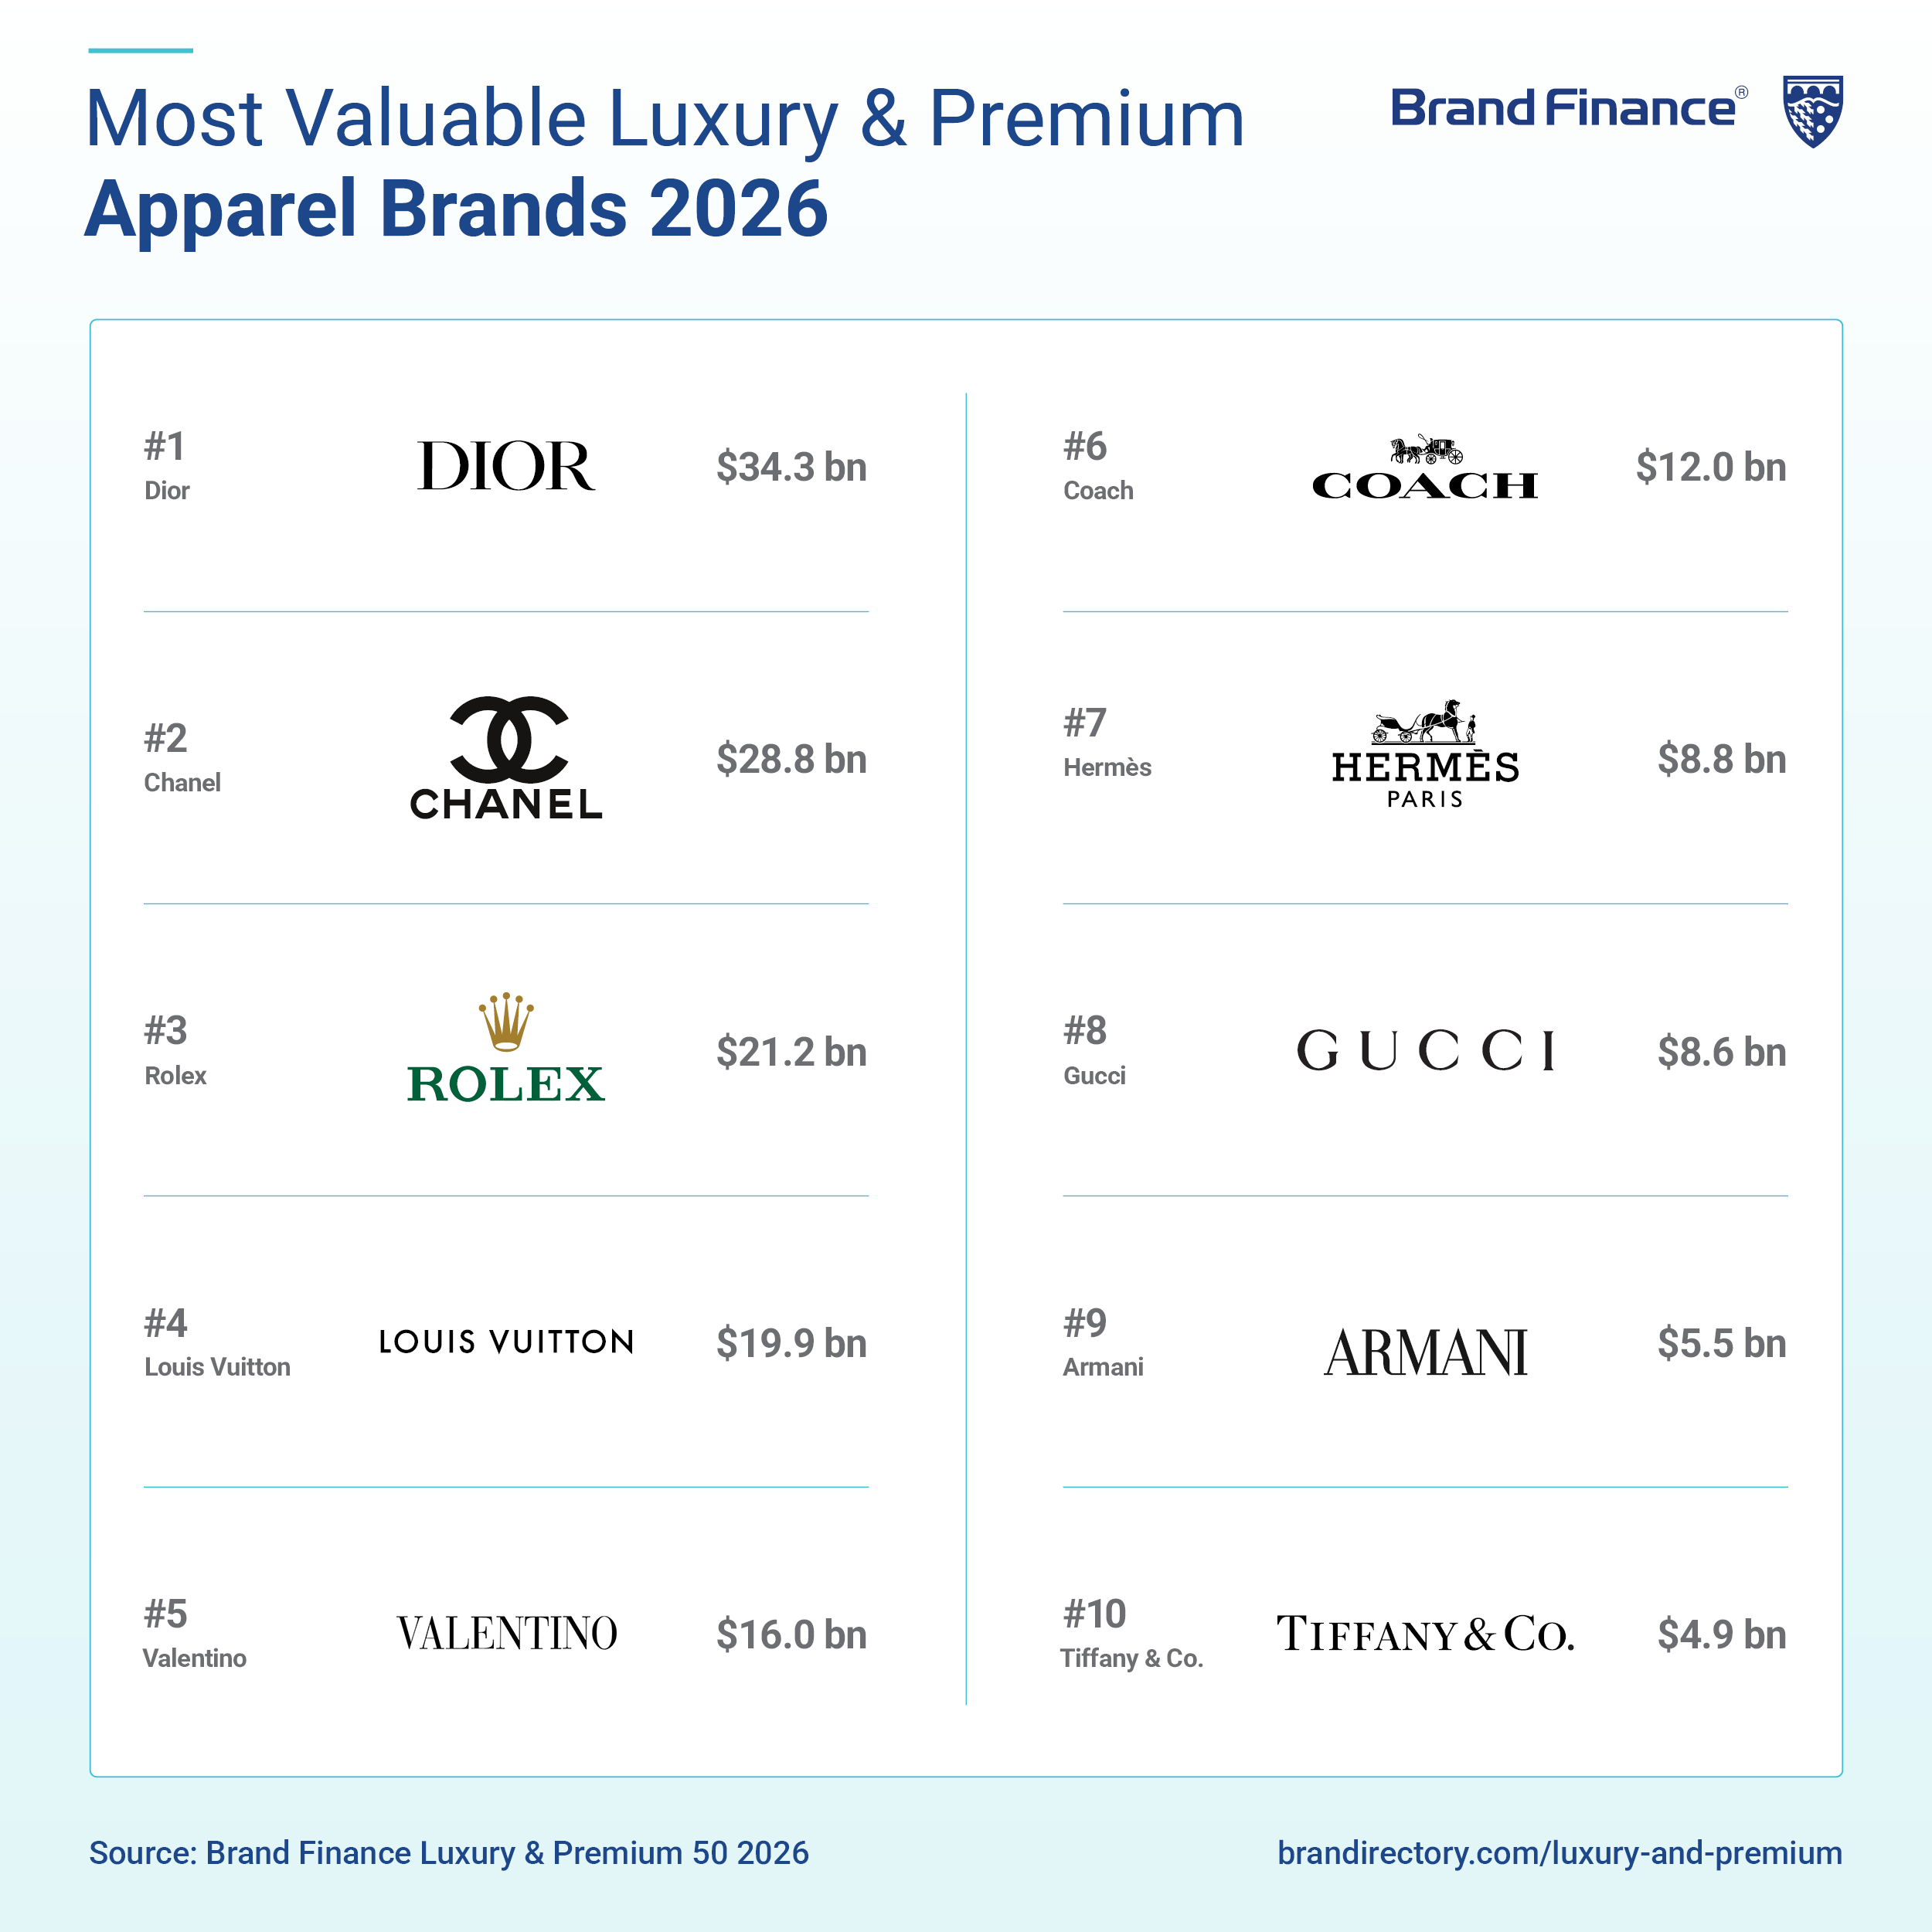
LONDON, 23 September 2026 – Apparel remains the largest luxury and premium segment with a total of 33 brands (one more than in 2025), according to the Luxury and Premium 50 2026 report by Brand Finance, the world’s leading brand valuation consultancy. Luxury and premium brand performance is becoming increasingly polarised, with traditional luxury categories facing pressure while automobiles, hotels, and, champagne and wine demonstrate greater resilience amid a broader shift in consumer spending towards experiences. In addition, luxury brands significantly outperformed their mass-market counterparts in the years following COVID-19, rebounding faster and delivering stronger cumulative growth that slowed in the past year.
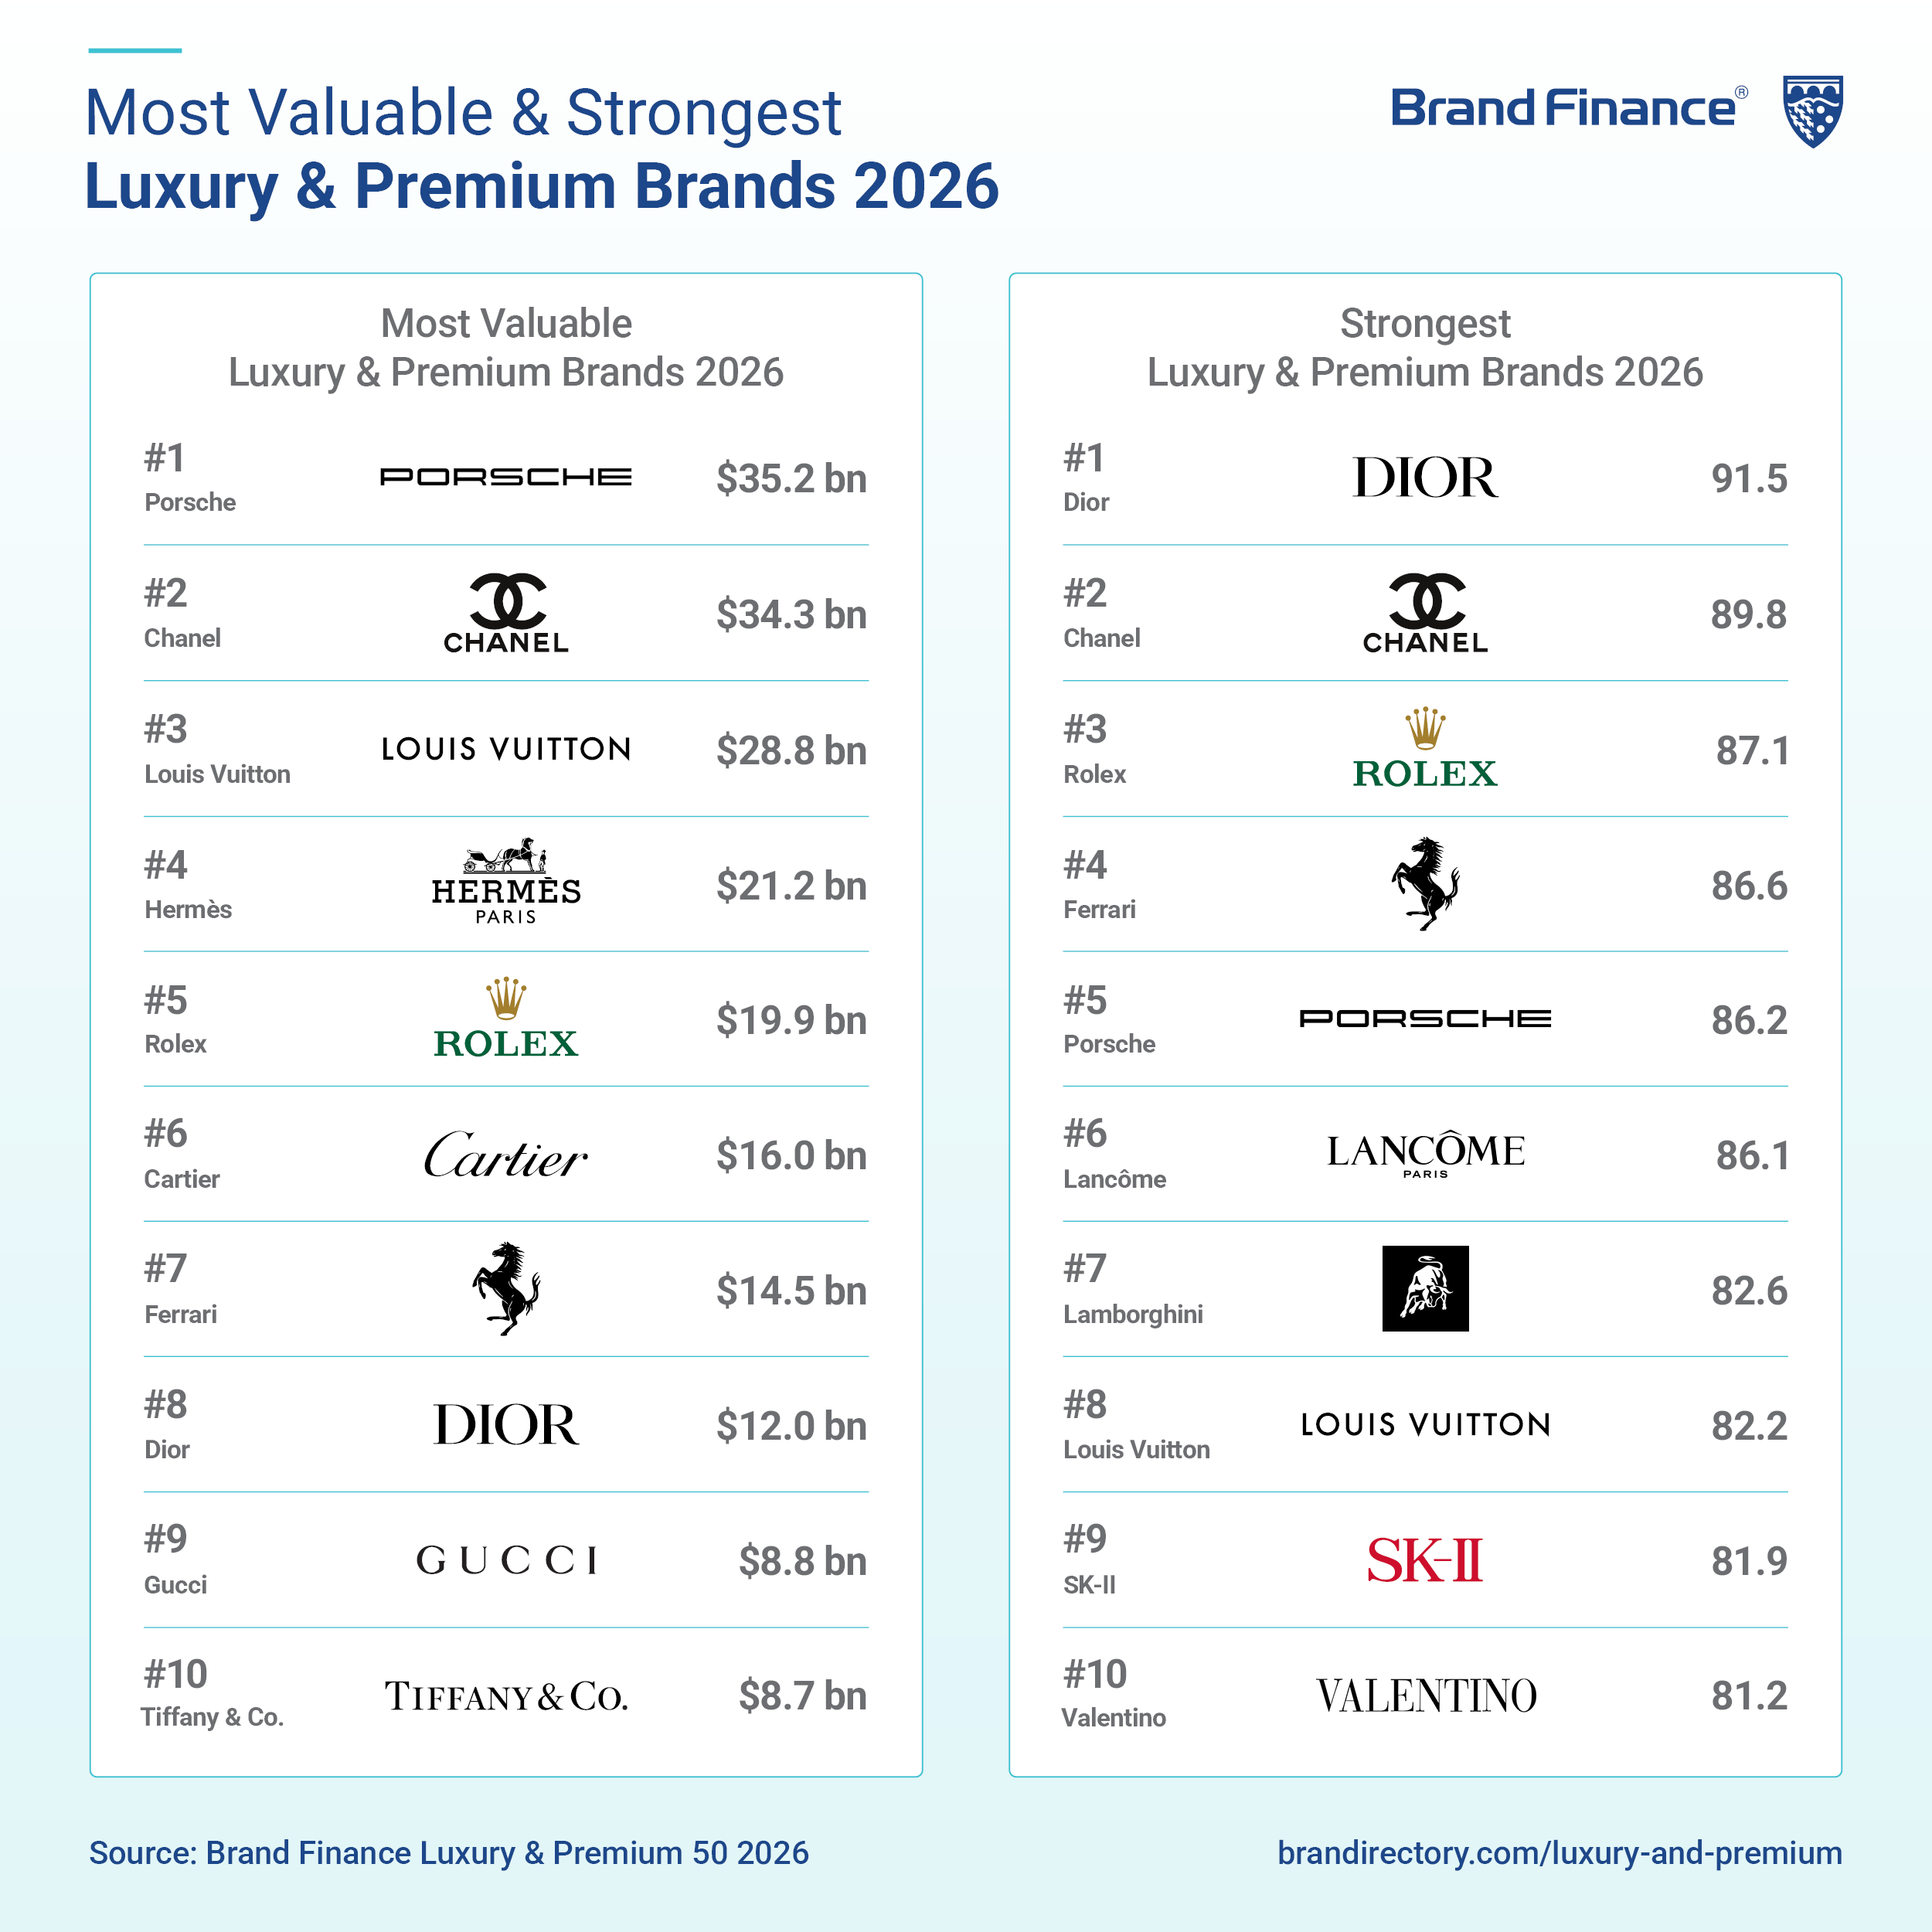
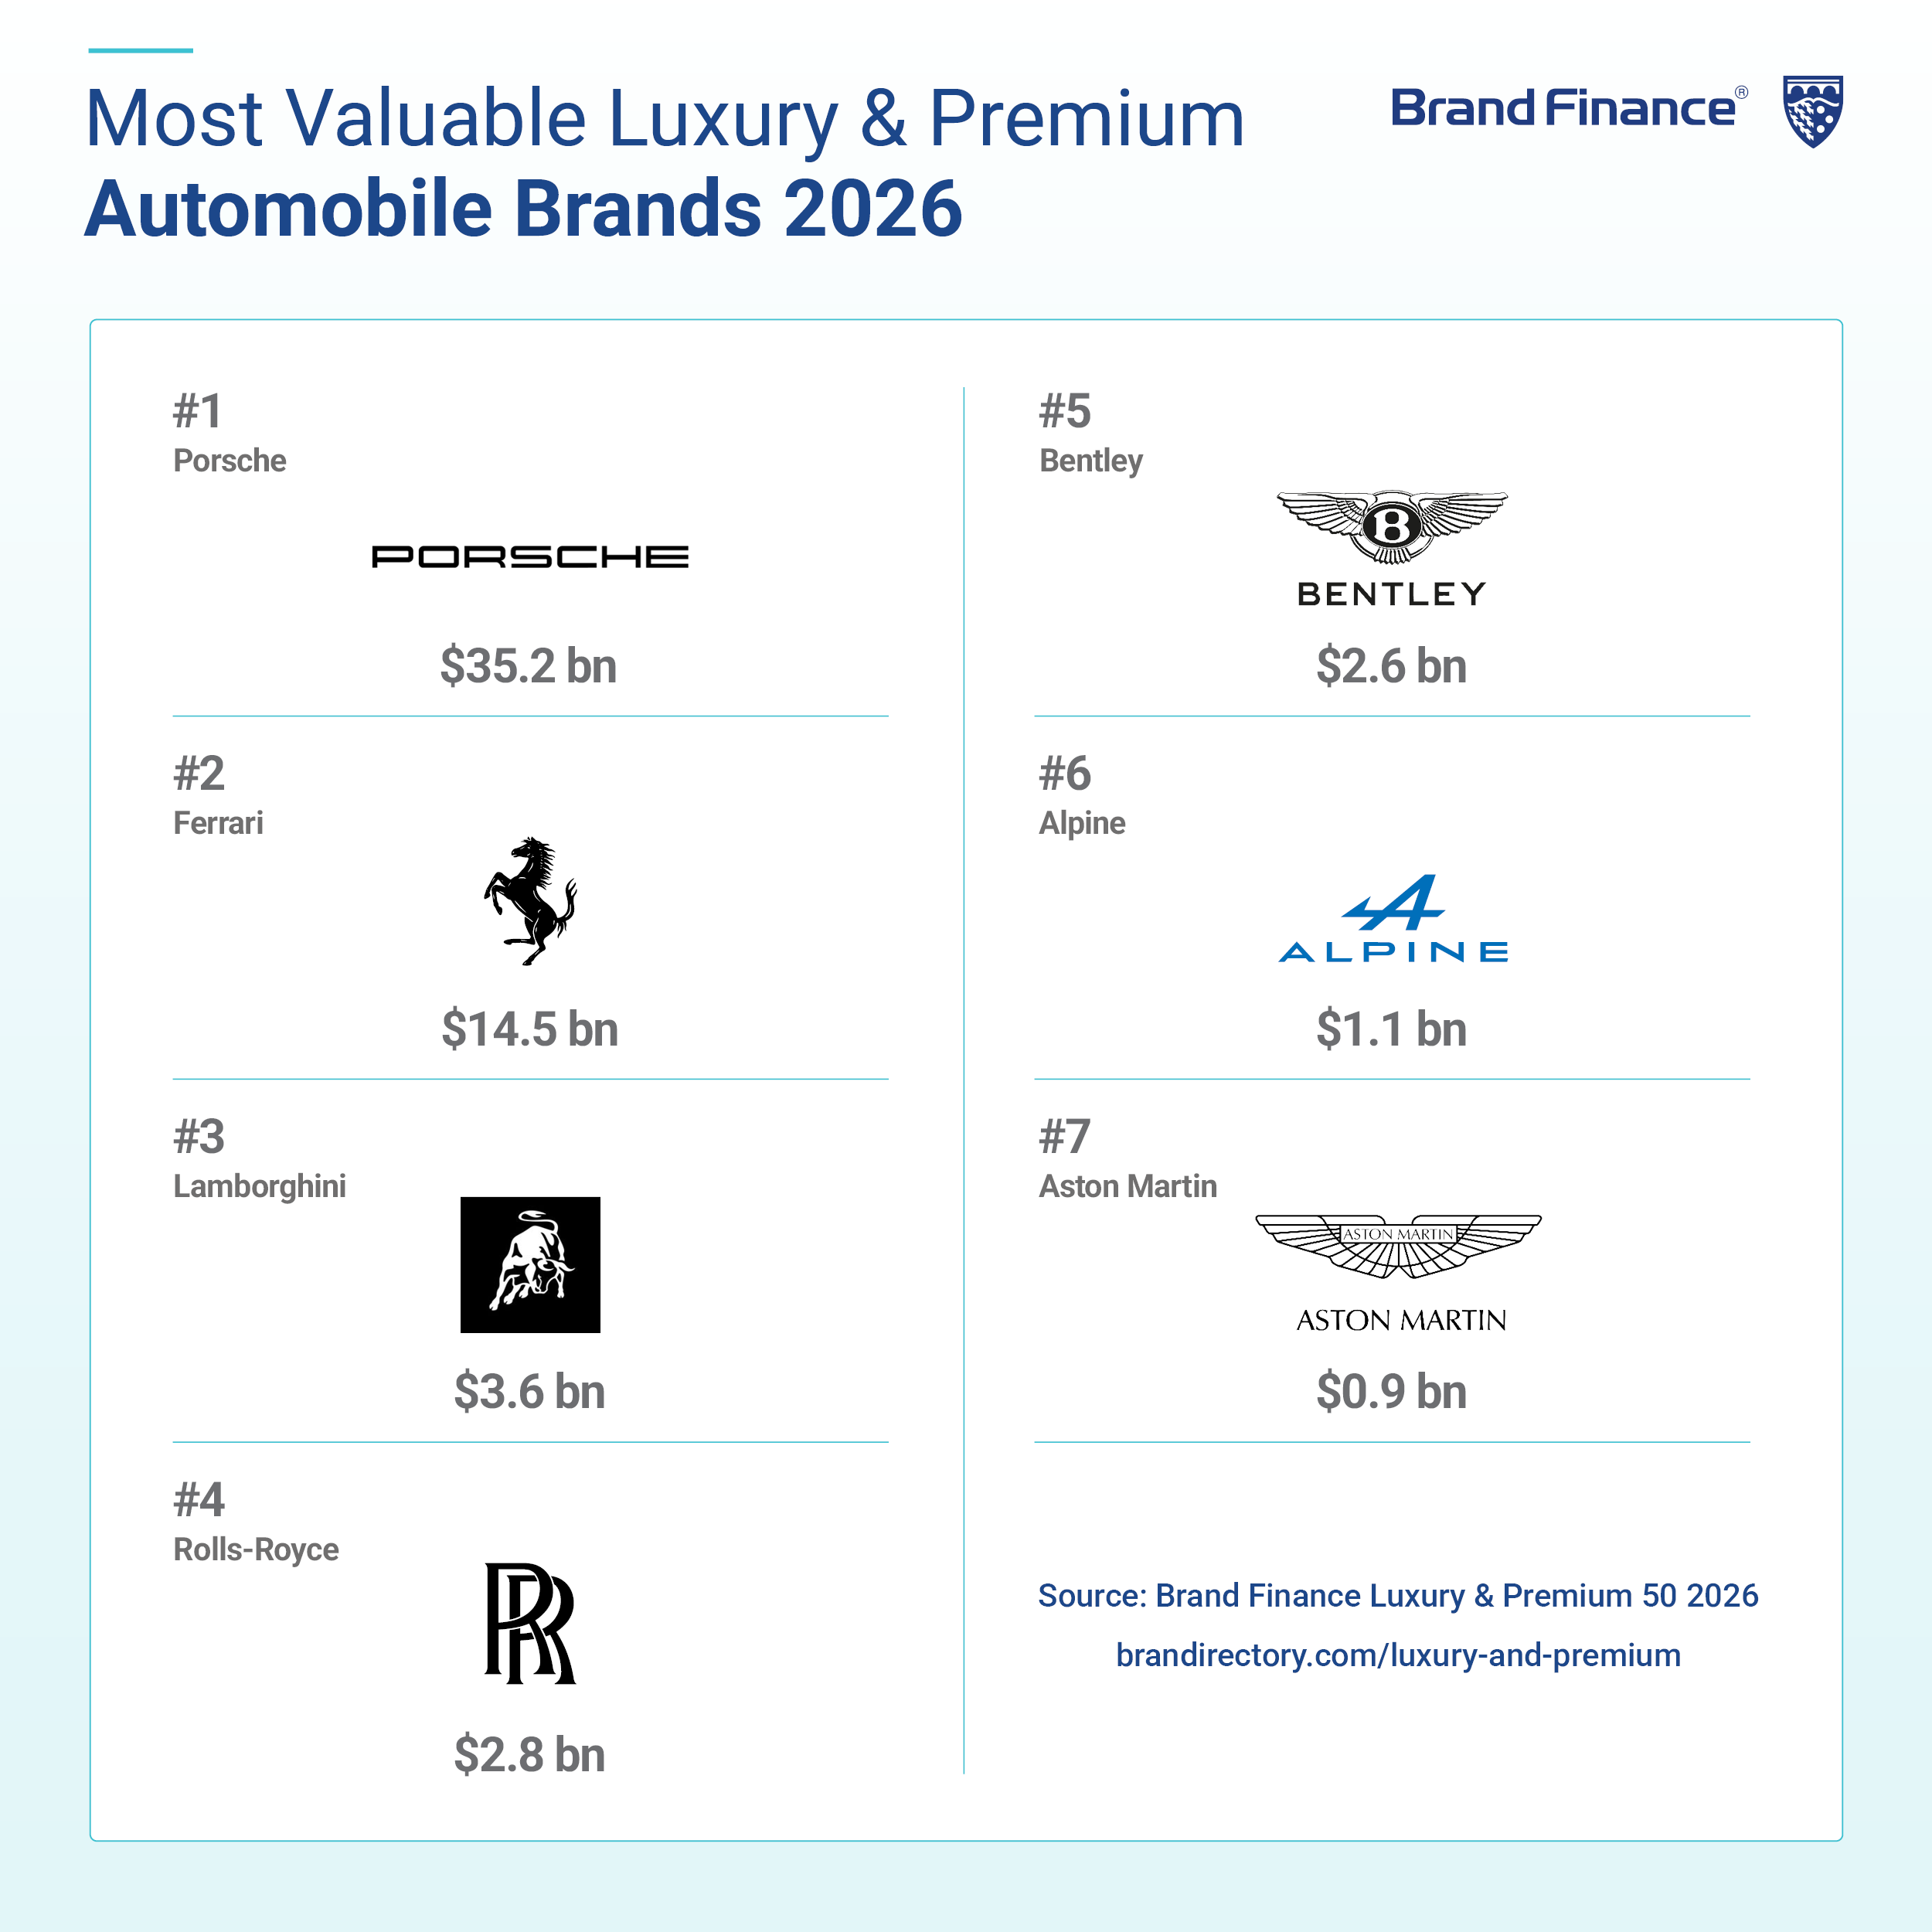
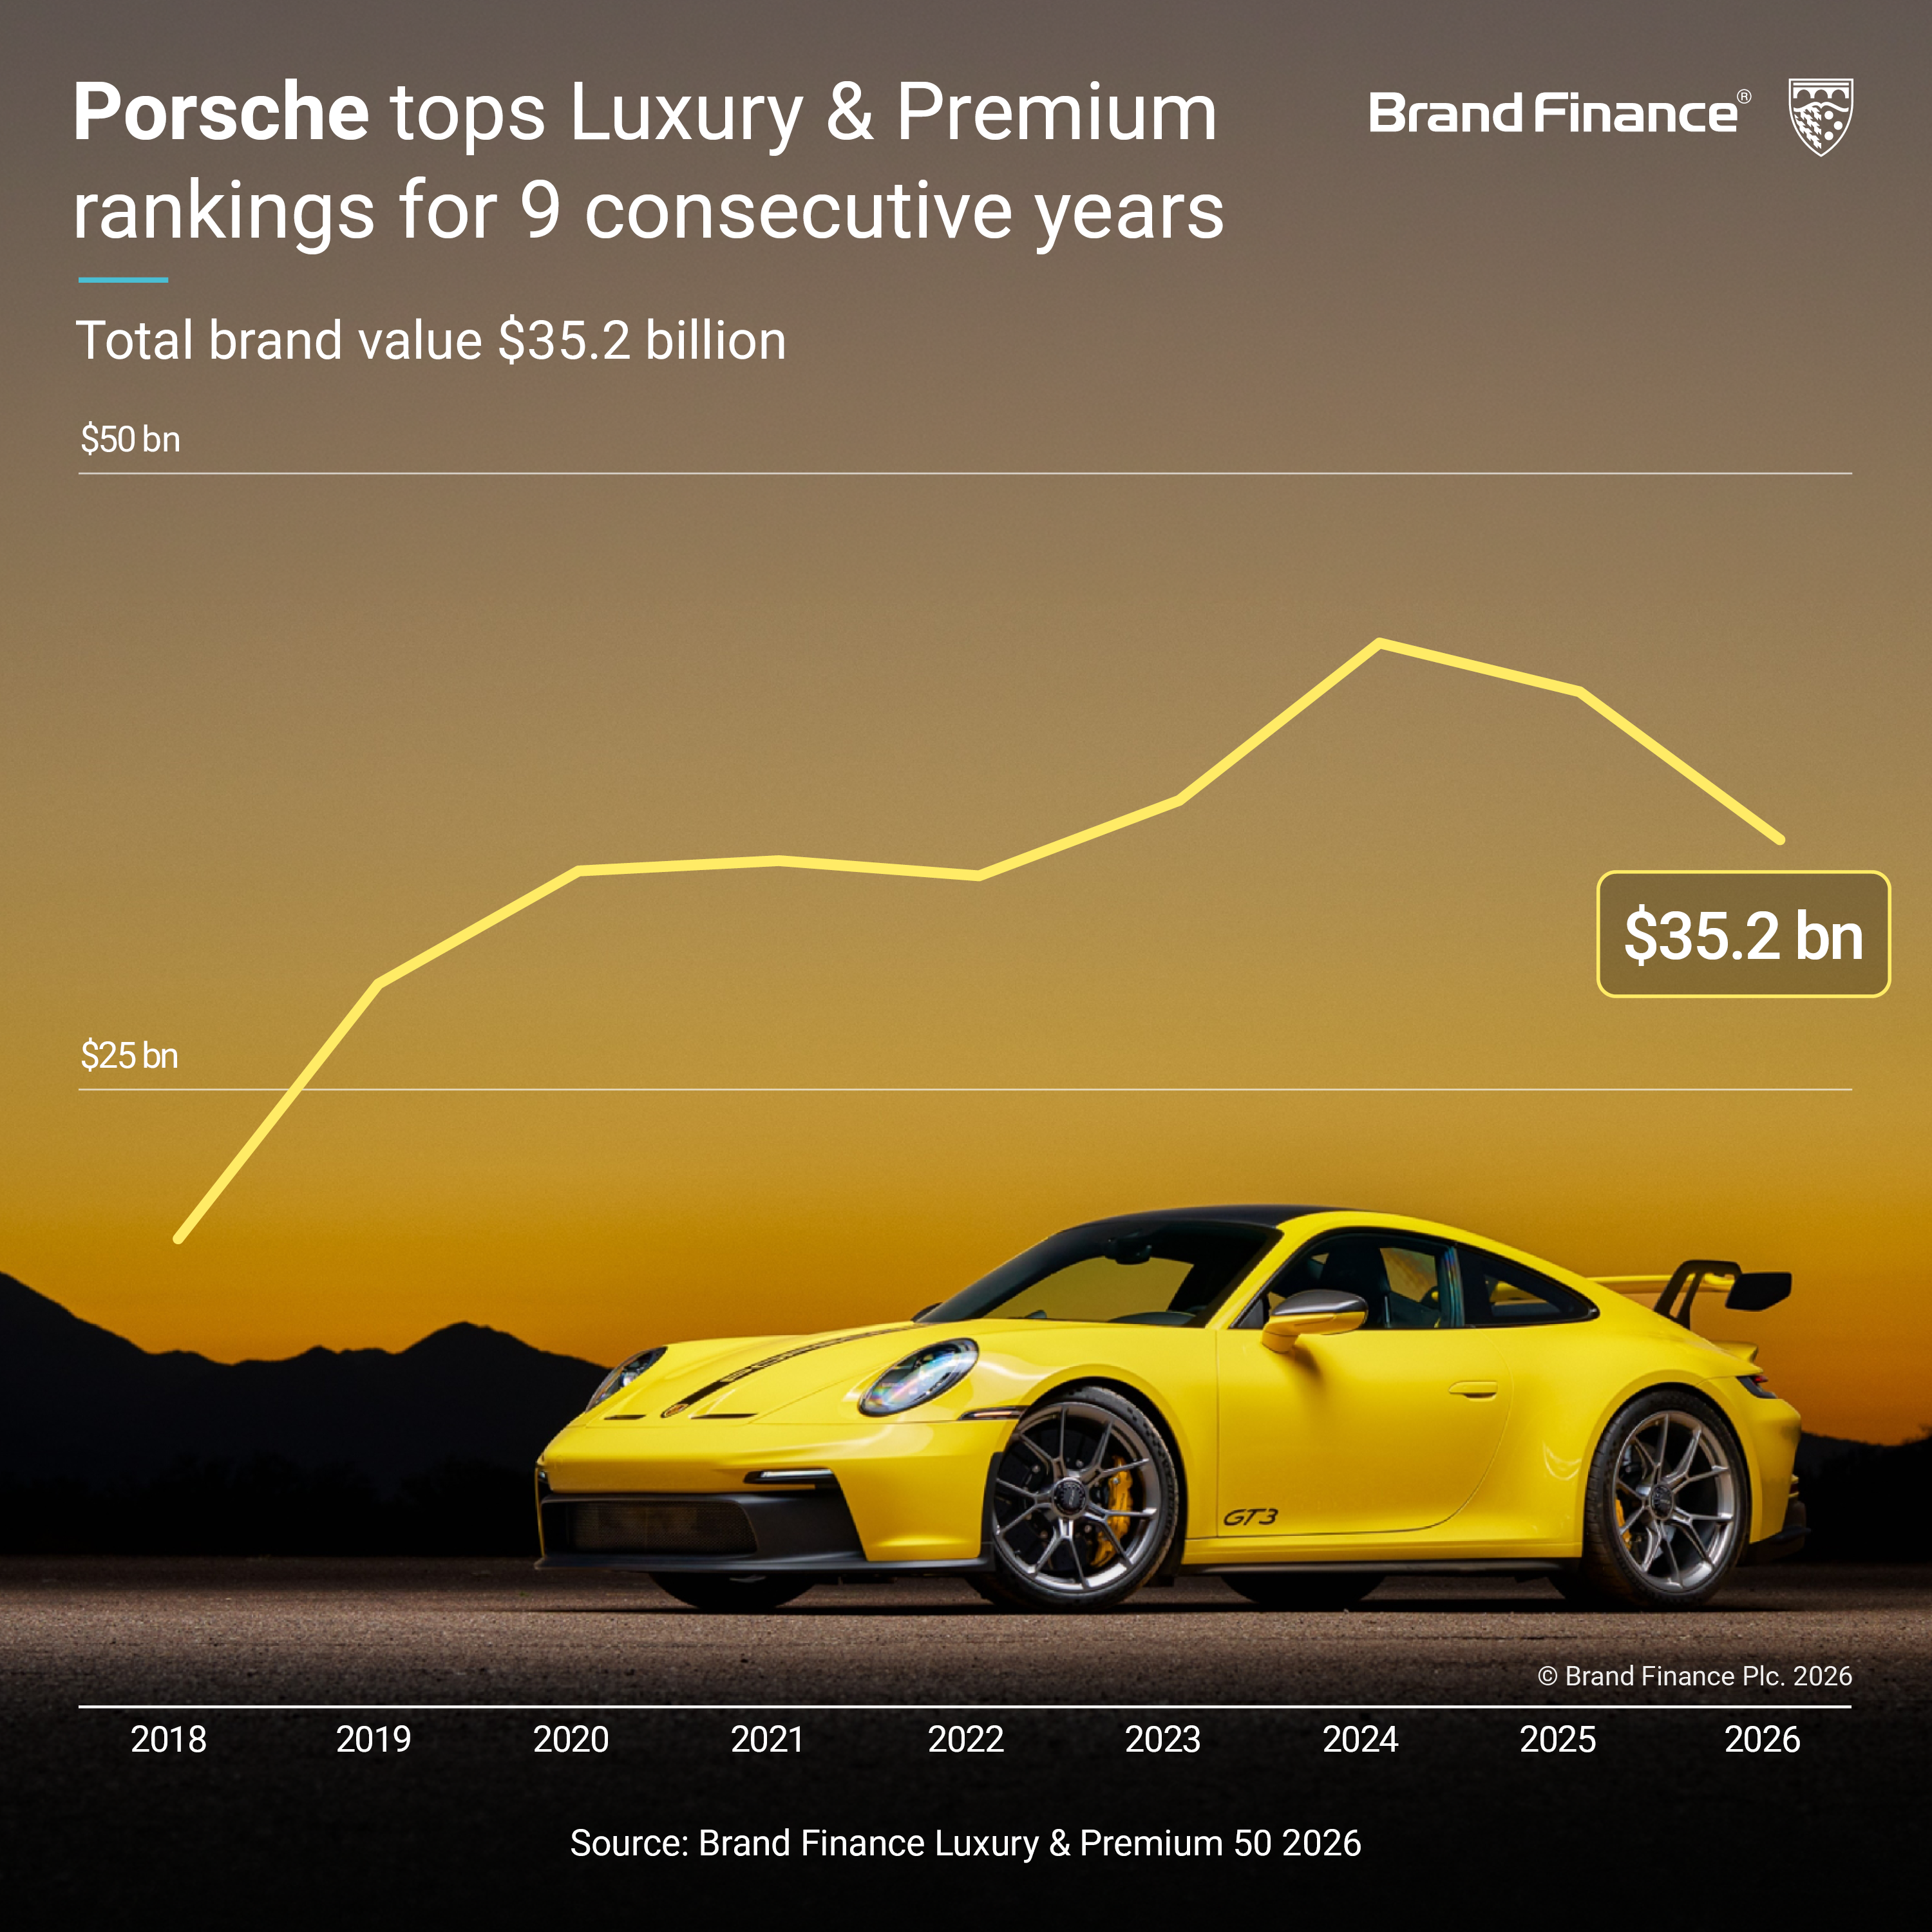
Porsche (brand value down 15% to USD35.2 billion) remains the world's most valuable luxury and premium brand in 2026 for the ninth consecutive year despite headwinds including weaker demand in China, US tariff pressures, lower profitability, and costs associated with its EV strategy reset. Under CEO Michael Leiters, the brand is focused on restructuring operations and strengthening long-term competitiveness.
Chanel (brand value down 9% to USD34.3 billion) ranks second globally as softer demand in China and the US, weakness in China's leather goods market, and sustained price increases weighed on performance. Despite this, Chanel continues to demonstrate strong consumer appeal, with near-perfect familiarity and reputation scores in China and strong results in France and the UK.
Louis Vuitton (brand value down 12% to USD28.8 billion) holds on to third place in the ranking. The brand was impacted by reduced tourist spending, economic uncertainty, and softer demand in China, which weighed on LVMH's Fashion & Leather Goods division. Nevertheless, Louis Vuitton continues to reinforce its premium positioning through sustained brand investment and creative continuity, with Japan remaining its strongest market.
Dior (brand value down 31% to USD12 billion) with a Brand Strengh Index (BSI) score of 91.5/100) retains its position as the strongest luxury and premium brand globally and is the only brand in the ranking to achieve a BSI score above 90, earning an AAA+ brand strength rating. Its performance is supported by exceptionally high familiarity and consideration scores in key markets, particularly China and the UK, alongside continued global brand visibility through major activations and exhibitions. Chanel (brand value down 9% to USD34.3 billion) ranks second with a BSI score of 89.8/100 and an AAA+ brand strength rating, supported by exceptionally strong consumer perceptions in China, France, and the UK. Rolex (brand value up 6% to USD19.9 billion) completes the top three strongest brands with a BSI score of 87.1/100 and an AAA brand strength rating, benefiting from its global prestige, exclusivity, and extensive sponsorship portfolio.
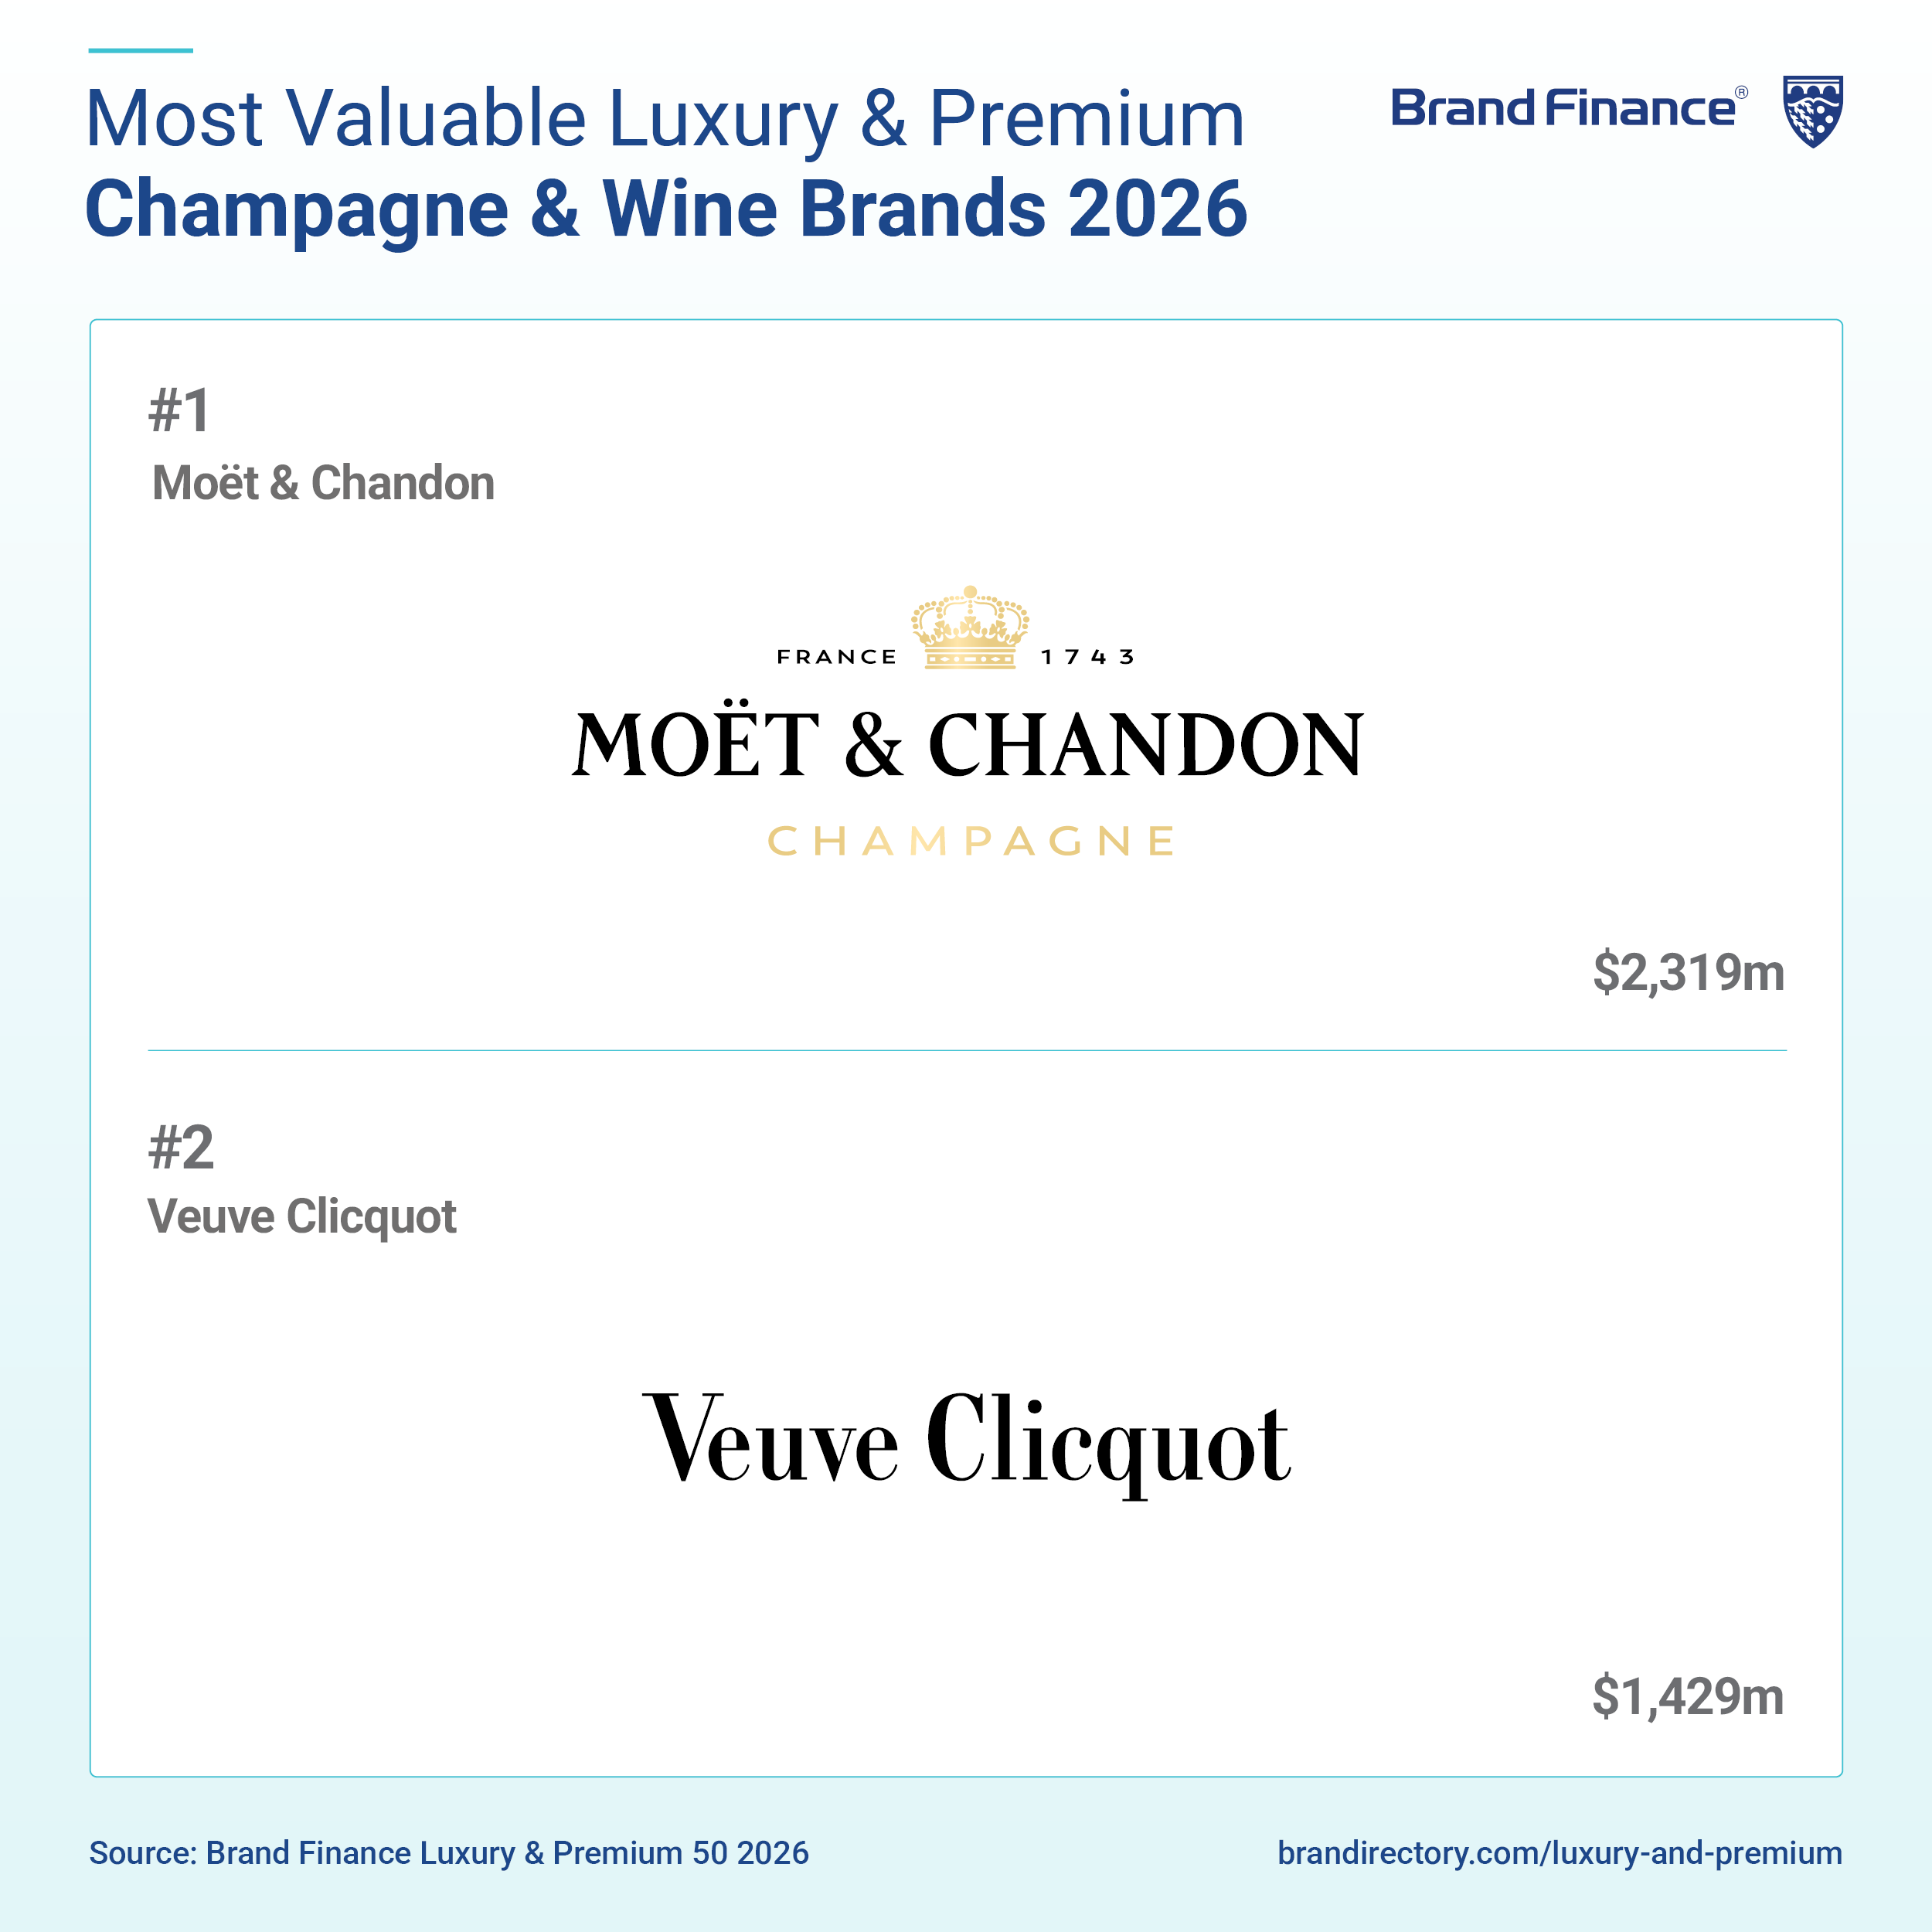
Veuve Clicquot (brand value up 39% to USD1.4 billion) is the fastest-growing luxury and premium brand in 2026. The brand achieved a BSI score of 74.7/100, up from 59.2/100 in 2025, earning an AA+ brand strength rating. Growth was supported by stronger consumer engagement, rising cultural relevance, improvements across key brand strength metrics, and favourable conditions within the champagne segment. France remains its strongest market, while improvements in the US contributed significantly to its momentum.
Henry Farr, Global Sector Head of Luxury and Premium, Brand Finance, commented:
“The 2026 luxury and premium landscape is increasingly defined by divergence. While apparel remains the sector's largest category, it has experienced a notable correction following several years of exceptional post-pandemic growth. At the same time, categories such as hotels, and, champagne & wine have continued to perform strongly as consumer preferences shift towards experiences, exclusivity, and personalisation. While luxury brands in several major categories have generally underperformed compared to their mass-market counterparts over the past year, this follows a period in which they significantly outpaced comparable non-luxury brands and delivered exceptional cumulative growth. The sector's recent slowdown should not be mistaken for a collapse in demand. More than half of luxury brands in comparable sectors continue to grow in value, highlighting an environment in which the strongest brands are differentiating themselves through clear positioning, brand investment, and their ability to adapt to evolving consumer expectations.”
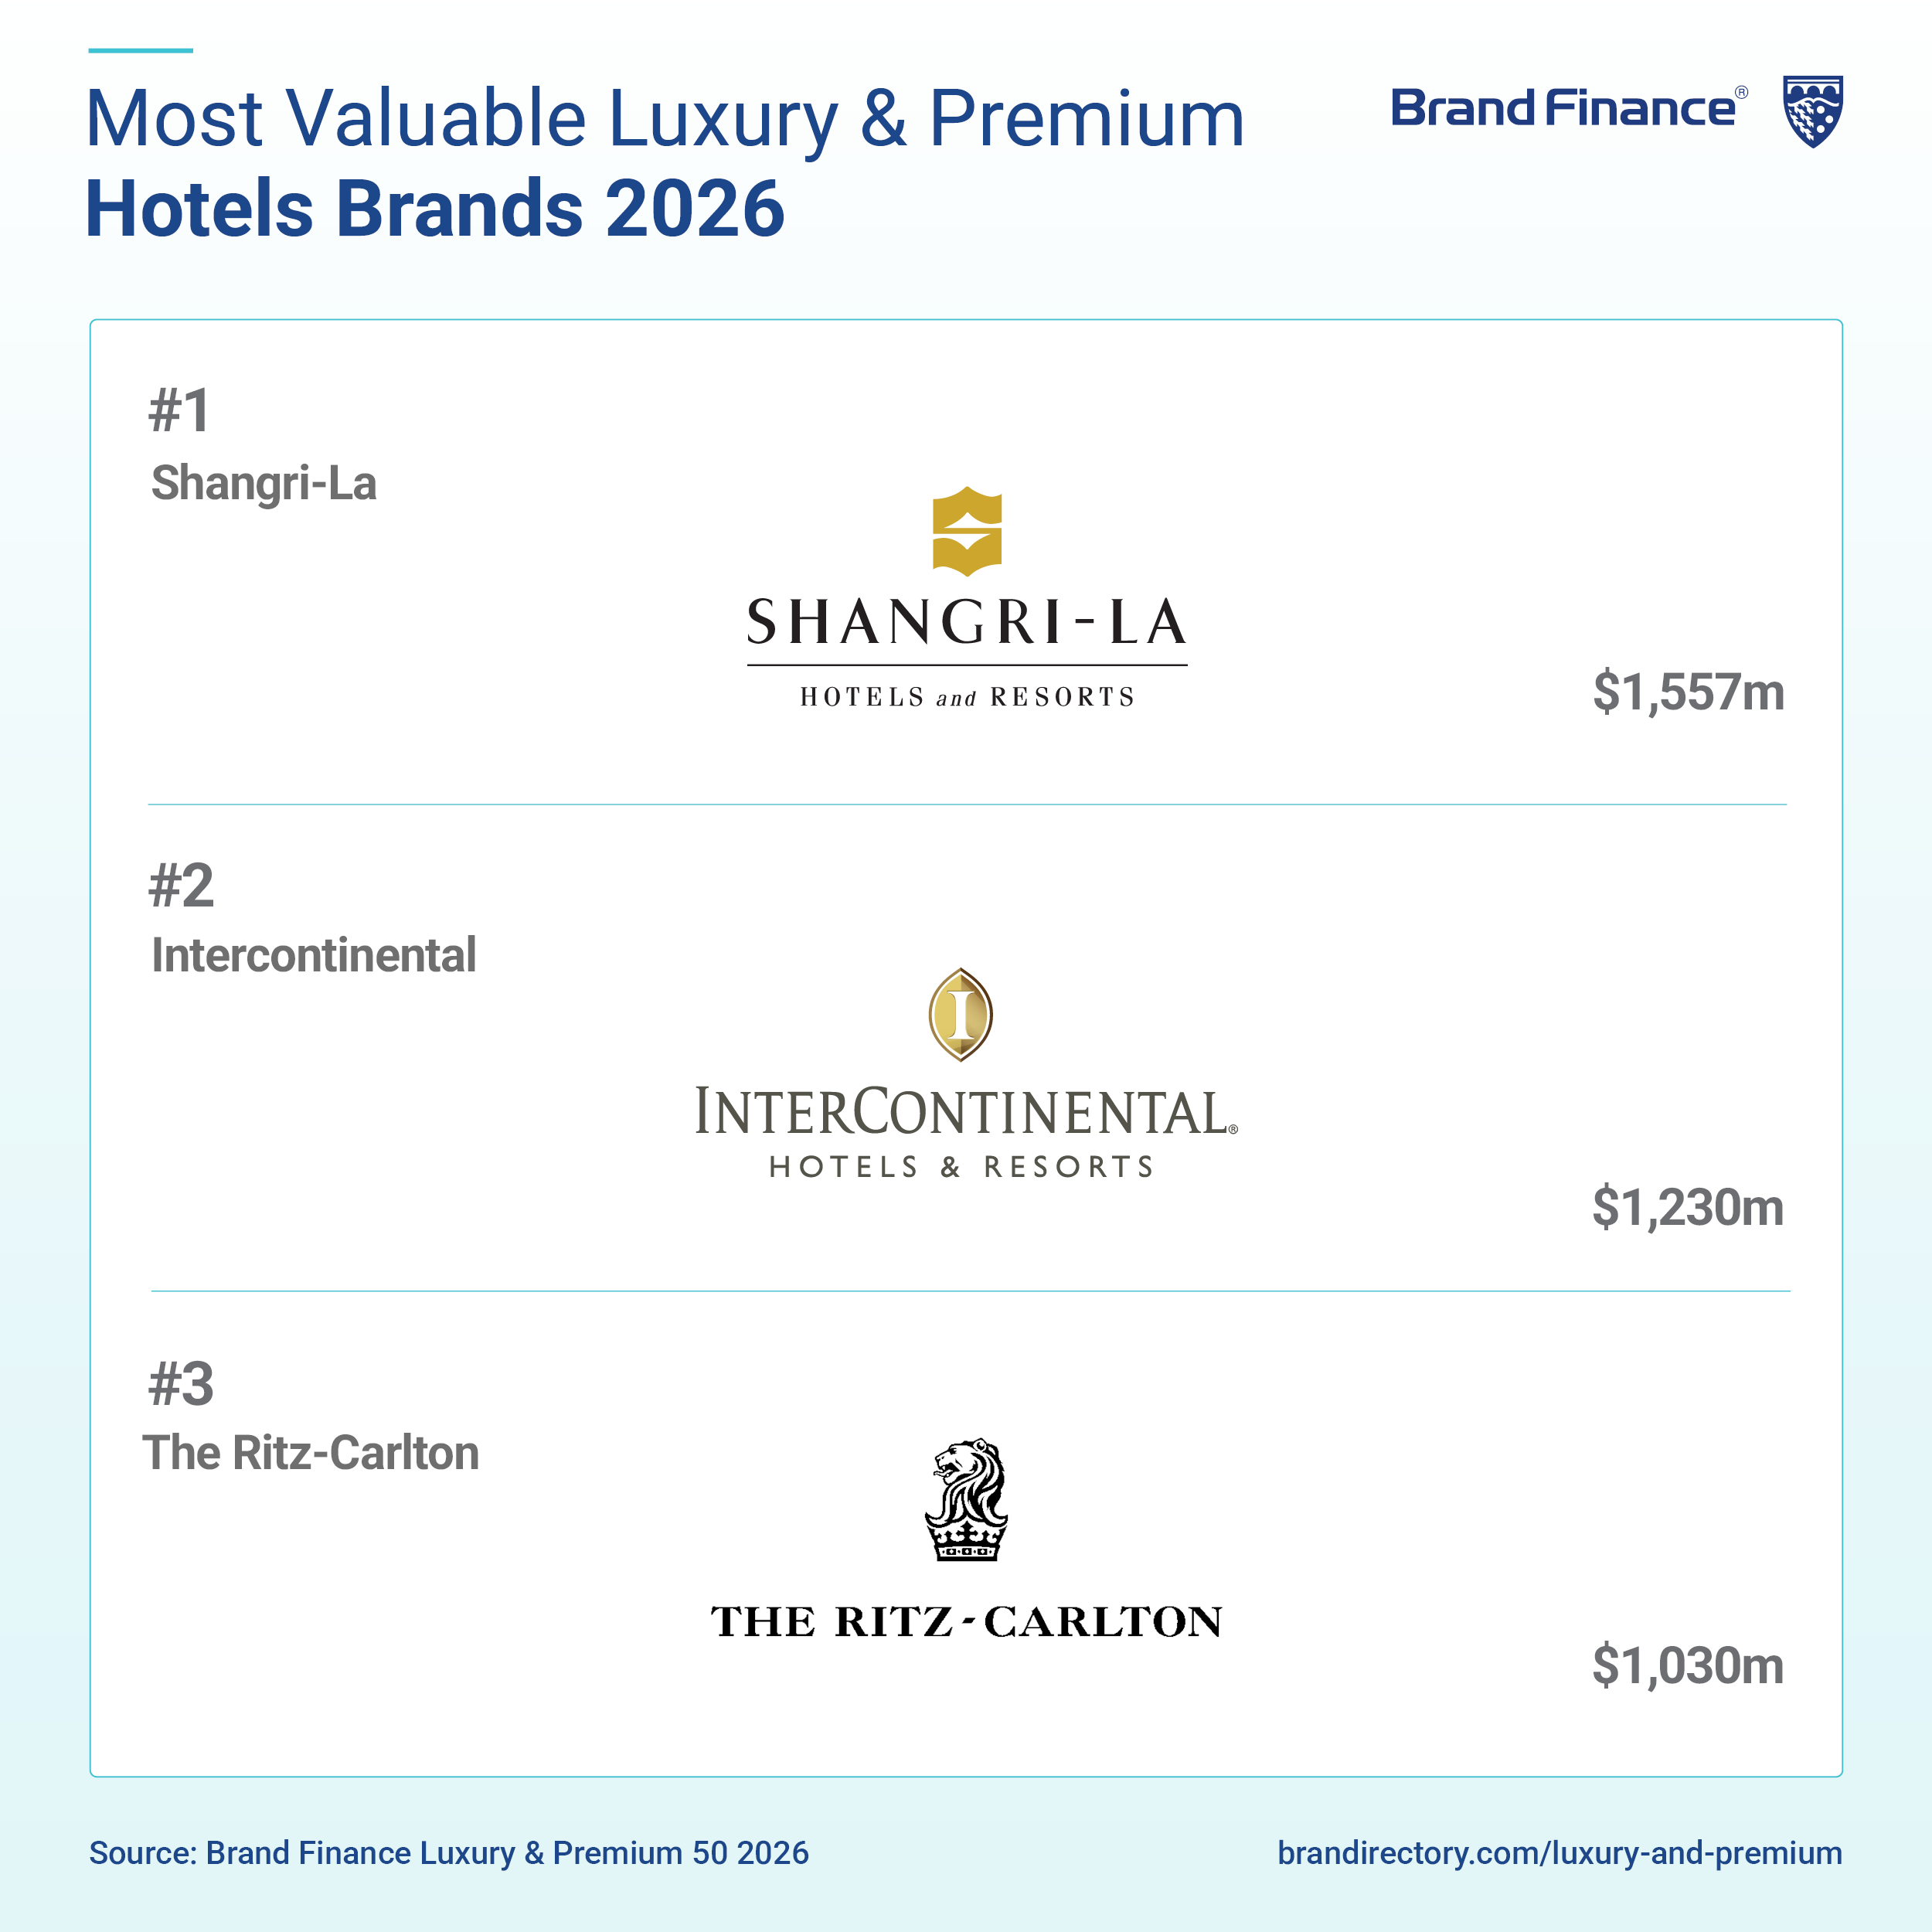
Among this year's brands to watch, Jaguar prepares for a major reinvention as an all-electric luxury marque with its highly anticipated Jaguar Type 01. Monte-Carlo Société des Bains de Mer (SBM) is also expanding as the group prepares to take its brand beyond Monaco for the first time, with a new hotel opening in Courchevel, and further destinations already under consideration. Alpine (brand value up 33% to USD1.1 billion) surpassed USD1 billion in brand value for the first time as Formula One visibility, product expansion, and electrification investments strengthened its premium positioning, while Shangri-La (brand value up 3% to USD1.6 billion) continues to reinforce its luxury credentials through premium hospitality experiences and service excellence.
Scott Chen, Managing Director, Brand Finance China, commented:
"China continues to advance high-standard opening-up and optimises its visa exemption policies, attracting global tourists to visit China and experience its development firsthand. Against this backdrop, the hotel industry has become an increasingly vital window for external opening. The remarkable achievements made by Shangri-La this year serve as a microcosm of the development of China’s high-end hospitality brands. Leveraging this opportunity, domestic brands should continuously enhance their brand value and strive to join the ranks of the world’s first-class brands.”
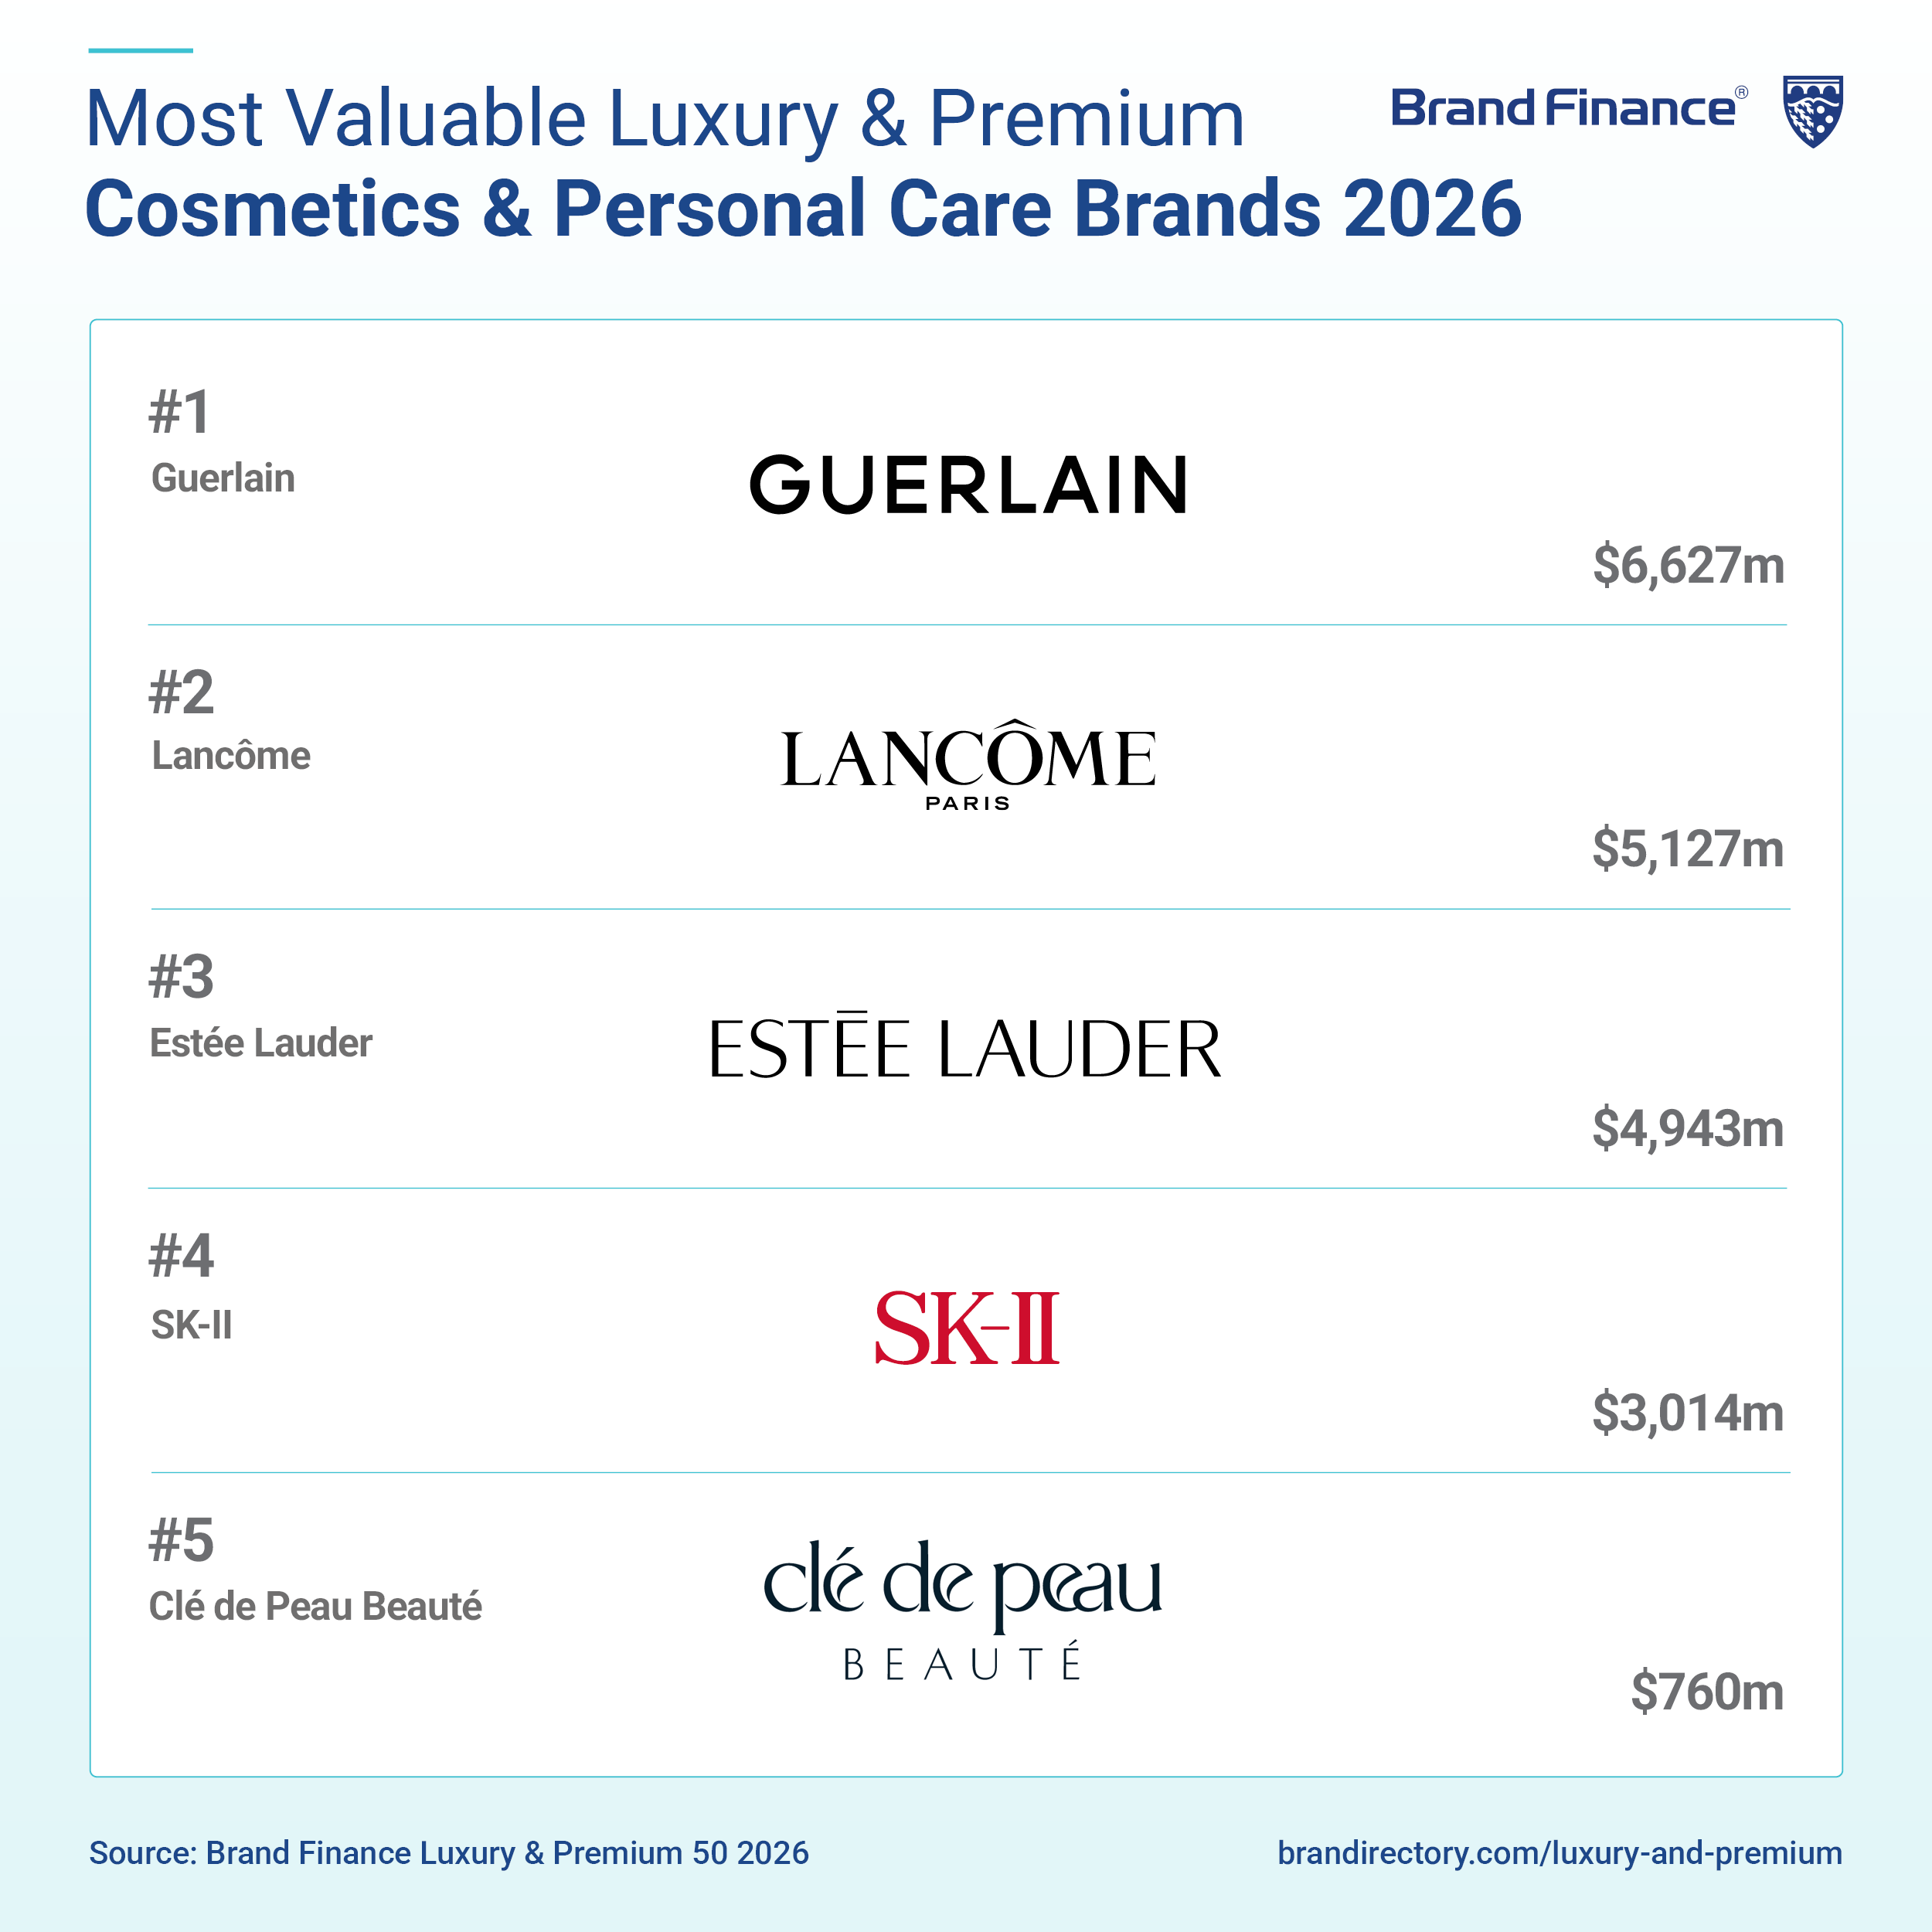
Sustainability continues to shape consumer perceptions across the luxury and premium sector, although its influence varies significantly by category. It is most important in luxury auto (22%) and champagne & wine (19%) sectors, followed by luxury cosmetics (7%), Hotels (7%), and Luxury Apparel (4%). In the 2026 Brand Finance Sustainability Perceptions Index, Bottega Veneta leads on luxury and premium brands for environmental sustainability perceptions, Coach leads on social sustainability perceptions, and Jaeger-LeCoultre leads on governance sustainability perceptions, highlighting the growing importance of sustainability in strengthening brand reputation and consumer trust.


Brand Finance is the world’s leading brand valuation consultancy. Bridging the gap between marketing and finance, Brand Finance evaluates the strength of brands and quantifies their financial value to help organisations make strategic decisions.
Headquartered in London, Brand Finance operates in over 25 countries. Every year, Brand Finance conducts more than 6,000 brand valuations, supported by original market research, and publishes over 100 reports which rank brands across all sectors and countries.
Brand Finance also operates the Global Brand Equity Monitor, conducting original market research annually on 6,000 brands, surveying more than 175,000 respondents across 41 countries and 31 industry sectors. By combining perceptual data from the Global Brand Equity Monitor with data from its valuation database — the largest brand value database in the world — Brand Finance equips ambitious brand leaders with the data, analytics, and the strategic guidance they need to enhance brand and business value.
In addition to calculating brand value, Brand Finance also determines the relative strength of brands through a balanced scorecard of metrics, compliant with ISO 20671.
Brand Finance is a regulated accountancy firm and a committed leader in the standardisation of the brand valuation industry. Brand Finance was the first to be certified by independent auditors as compliant with both ISO 10668 and ISO 20671 and has received the official endorsement of the Marketing Accountability Standards Board (MASB) in the United States.
Brand is defined as a marketing-related intangible asset including, but not limited to, names, terms, signs, symbols, logos, and designs, intended to identify goods, services, or entities, creating distinctive images and associations in the minds of stakeholders, thereby generating economic benefits.
Brand strength is the efficacy of a brand’s performance on intangible measures relative to its competitors. Brand Finance evaluates brand strength in a process compliant with ISO 20671, looking at Marketing Investment, Stakeholder Equity, and the impact of those on Business Performance. The data used is derived from Brand Finance’s proprietary market research programme and from publicly available sources.
Each brand is assigned a Brand Strength Index (BSI) score out of 100, which feeds into the brand value calculation. Based on the score, each brand is assigned a corresponding Brand Rating up to AAA+ in a format similar to a credit rating.
Brand Finance calculates the values of brands in its rankings using the Royalty Relief approach – a brand valuation method compliant with the industry standards set in ISO 10668. It involves estimating the likely future revenues that are attributable to a brand by calculating a royalty rate that would be charged for its use, to arrive at a ‘brand value’ understood as a net economic benefit that a brand owner would achieve by licensing the brand in the open market.
The steps in this process are as follows:
1 Calculate brand strength using a balanced scorecard of metrics assessing Marketing Investment, Stakeholder Equity, and Business Performance. Brand strength is expressed as a Brand Strength Index (BSI) score on a scale of 0 to 100.
2 Determine royalty range for each industry, reflecting the importance of brand to purchasing decisions. In luxury, the maximum percentage is high, while in extractive industry, where goods are often commoditised, it is lower. This is done by reviewing comparable licensing agreements sourced from Brand Finance’s extensive database.
3 Calculate royalty rate. The BSI score is applied to the royalty range to arrive at a royalty rate. For example, if the royalty range in a sector is 0-5% and a brand has a BSI score of 80 out of 100, then an appropriate royalty rate for the use of this brand in the given sector will be 4%.
4 Determine brand-specific revenues by estimating a proportion of parent company revenues attributable to a brand.
5 Determine forecast revenues using a function of historic revenues, equity analyst forecasts, and economic growth rates.
6 Apply the royalty rate to the forecast revenues to derive brand revenues.
7 Discount post-tax brand revenues to a net present value which equals the brand value.
Brand Finance has produced this study with an independent and unbiased analysis. The values derived and opinions presented in this study are based on publicly available information and certain assumptions that Brand Finance used where such data was deficient or unclear. Brand Finance accepts no responsibility and will not be liable in the event that the publicly available information relied upon is subsequently found to be inaccurate. The opinions and financial analysis expressed in the study are not to be construed as providing investment or business advice. Brand Finance does not intend the study to be relied upon for any reason and excludes all liability to any body, government, or organisation.
The data presented in this study form part of Brand Finance's proprietary database, are provided for the benefit of the media, and are not to be used in part or in full for any commercial or technical purpose without written permission from Brand Finance.