This article was originally published in the Brand Finance Airlines 50 2026.
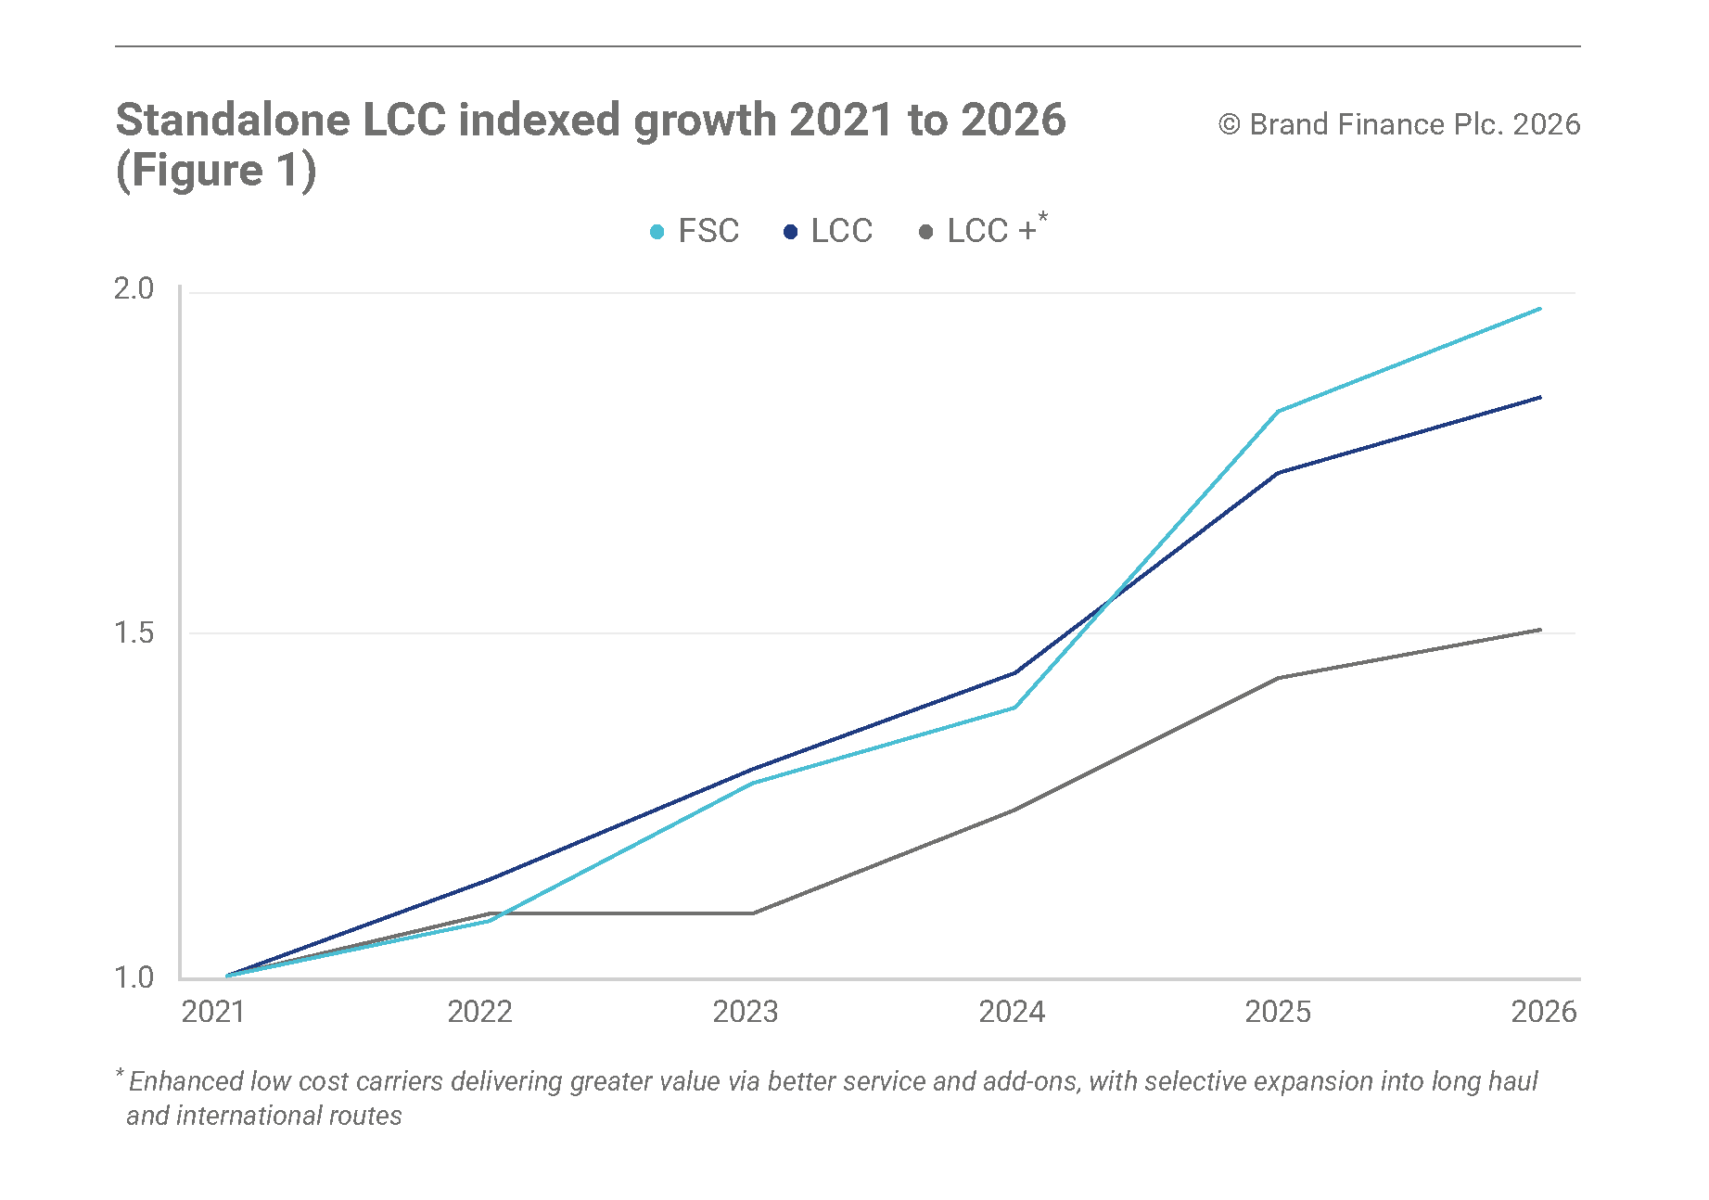
Low-cost carrier (LCC) brands are no longer operating on the fringes of the aviation sector. Across both standalone operators and low-cost subsidiaries within legacy airline groups, they have emerged as the faster growing segment of the industry, reshaping not only competitive dynamics but also the way brand value is created and sustained. Between 2020 and 2026, standalone LCCs have compounded brand value at a pace that increasingly challenges the traditional full-service model, while group owned LCC brands have, in many cases, outpaced the growth of their flagship counterparts on an indexed basis since the 2021 COVID slump. What was once considered a secondary layer within airline portfolios is now becoming more central to growth.
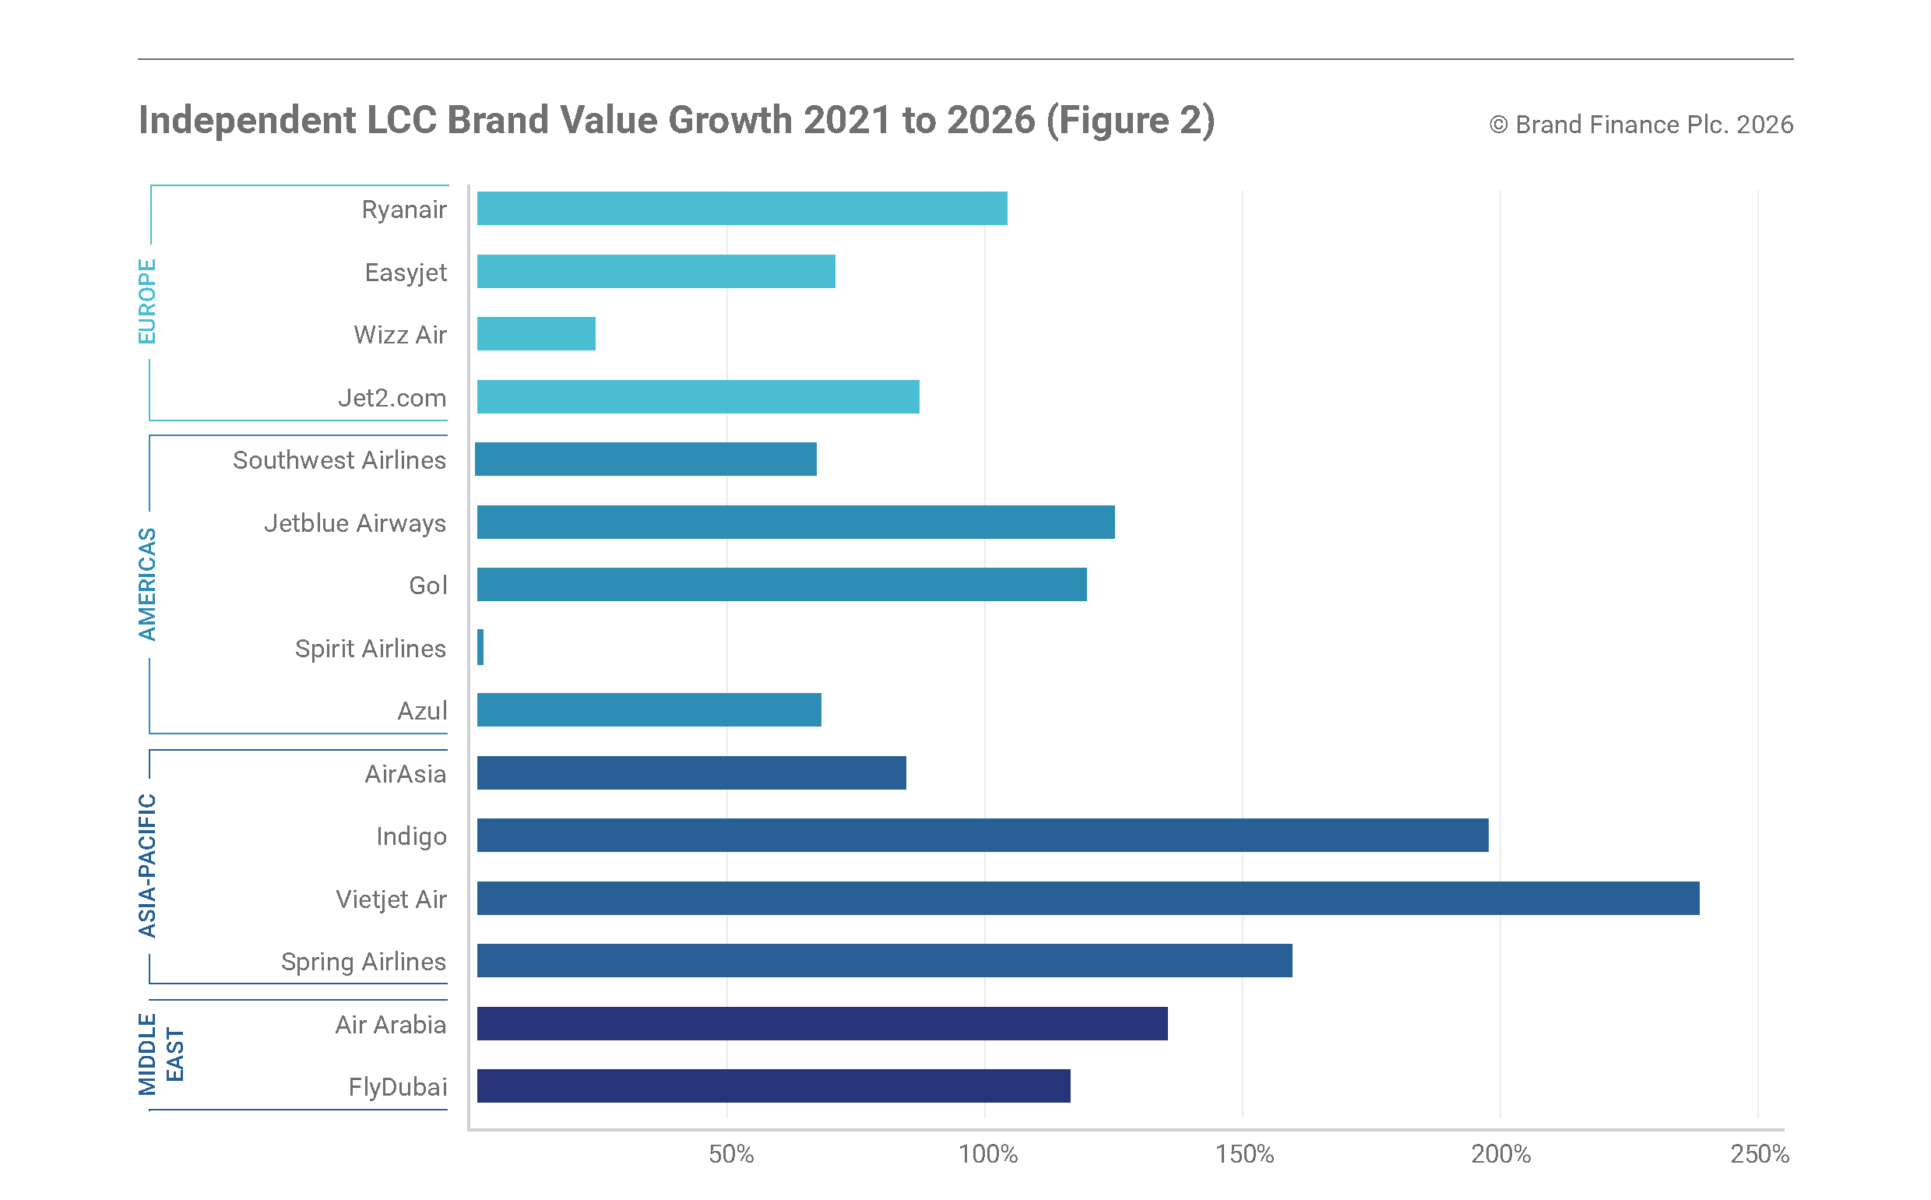
In Europe, the LCC market remains anchored by the scale and resilience of Ryanair and easyJet. Both brands have surpassed the USD2 billion mark and continue to grow steadily, reinforcing a durable duopoly in the region. Yet beneath this stability, divergence within the segment is becoming increasingly apparent. Wizz Air has declined by 24% from its 2020 peak, reflecting its exposure to Eastern European demand volatility and rising fleet related cost pressures. In contrast, Jet2.com has emerged as one of the most resilient performers, approaching the USD1 billion threshold. Its leisure focused model, closely aligned with post pandemic travel demand, has proven effective in capturing a market where discretionary, short haul travel has rebounded faster than corporate segments.
Asia Pacific presents the most compelling growth story. IndiGo has recorded strong and sustained brand value expansion since 2021, supported by the rapid structural growth of India’s domestic aviation market and continued capacity expansion. VietJet Air has benefited from the recovery in Southeast Asian tourism flows, while AirAsia, with a brand value of USD2.2 billion, remains the third most valuable LCC brand globally. Cebu Pacific is also gaining traction, supported by improving regional connectivity and strong outbound travel demand. The region’s growth reflects not only recovery, but expansion, with rising middle-class populations and improving infrastructure continuing to unlock new passenger volumes.
In the US, growth has been more measured, but the structural dynamics remain clear. Southwest Airlines continues to lead as the most valuable LCC brand globally at USD6.7 billion, although its growth trajectory has moderated. JetBlue Airways has recorded incremental gains, while Spirit Airlines has declined since 2020, offering a cautionary signal on the limits of the ultra low-cost model in an environment of rising operating costs and shifting customer expectations. The ability to balance affordability with experience is becoming increasingly important to sustaining brand strength.
Increasingly, US LCC’s appear to be evolving towards an ‘LCC+’ model, gradually enhancing their service offering to sit above traditional low-cost carriers. This includes greater emphasis on customer experience, seating options and ancillary services, as airlines seek to balance affordability with value. In this context, the ability to combine competitive pricing with a more differentiated, customer-centric proposition is becoming critical to sustaining brand strength.
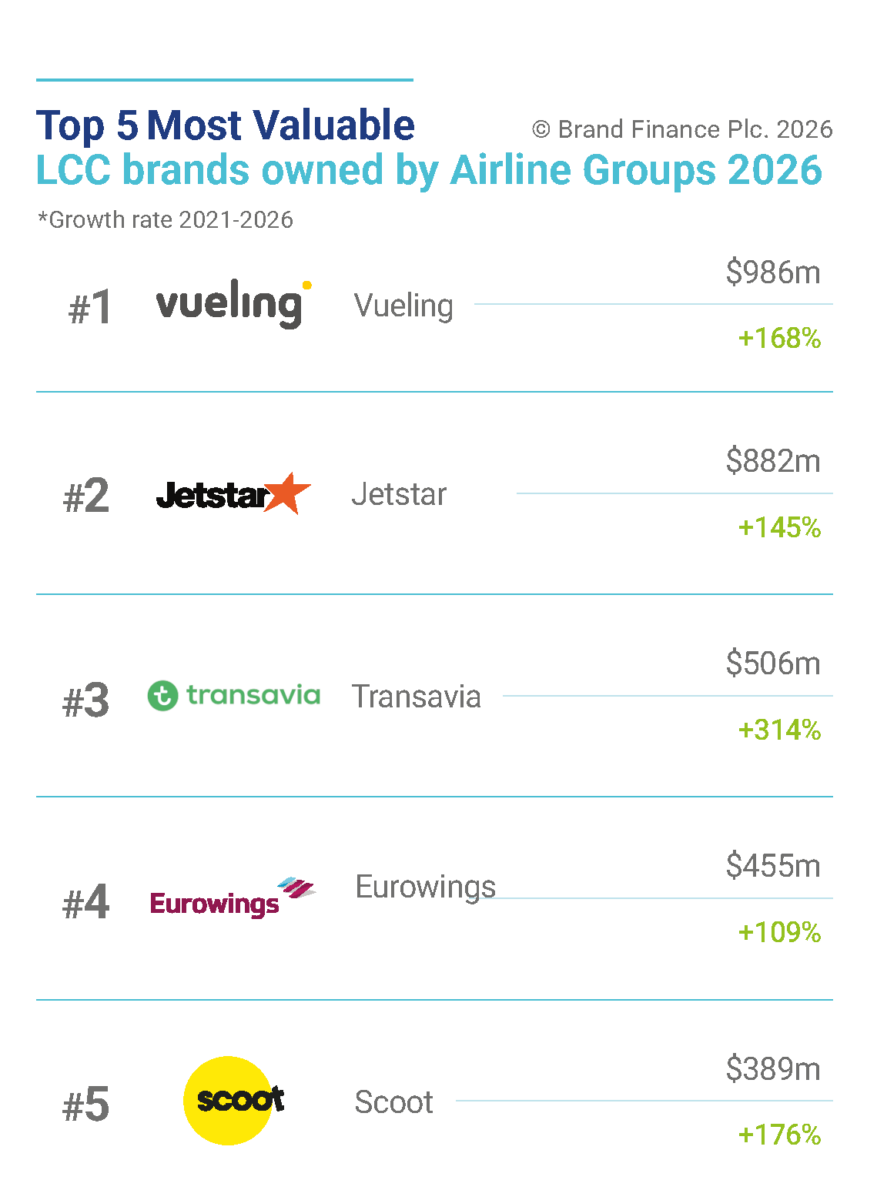
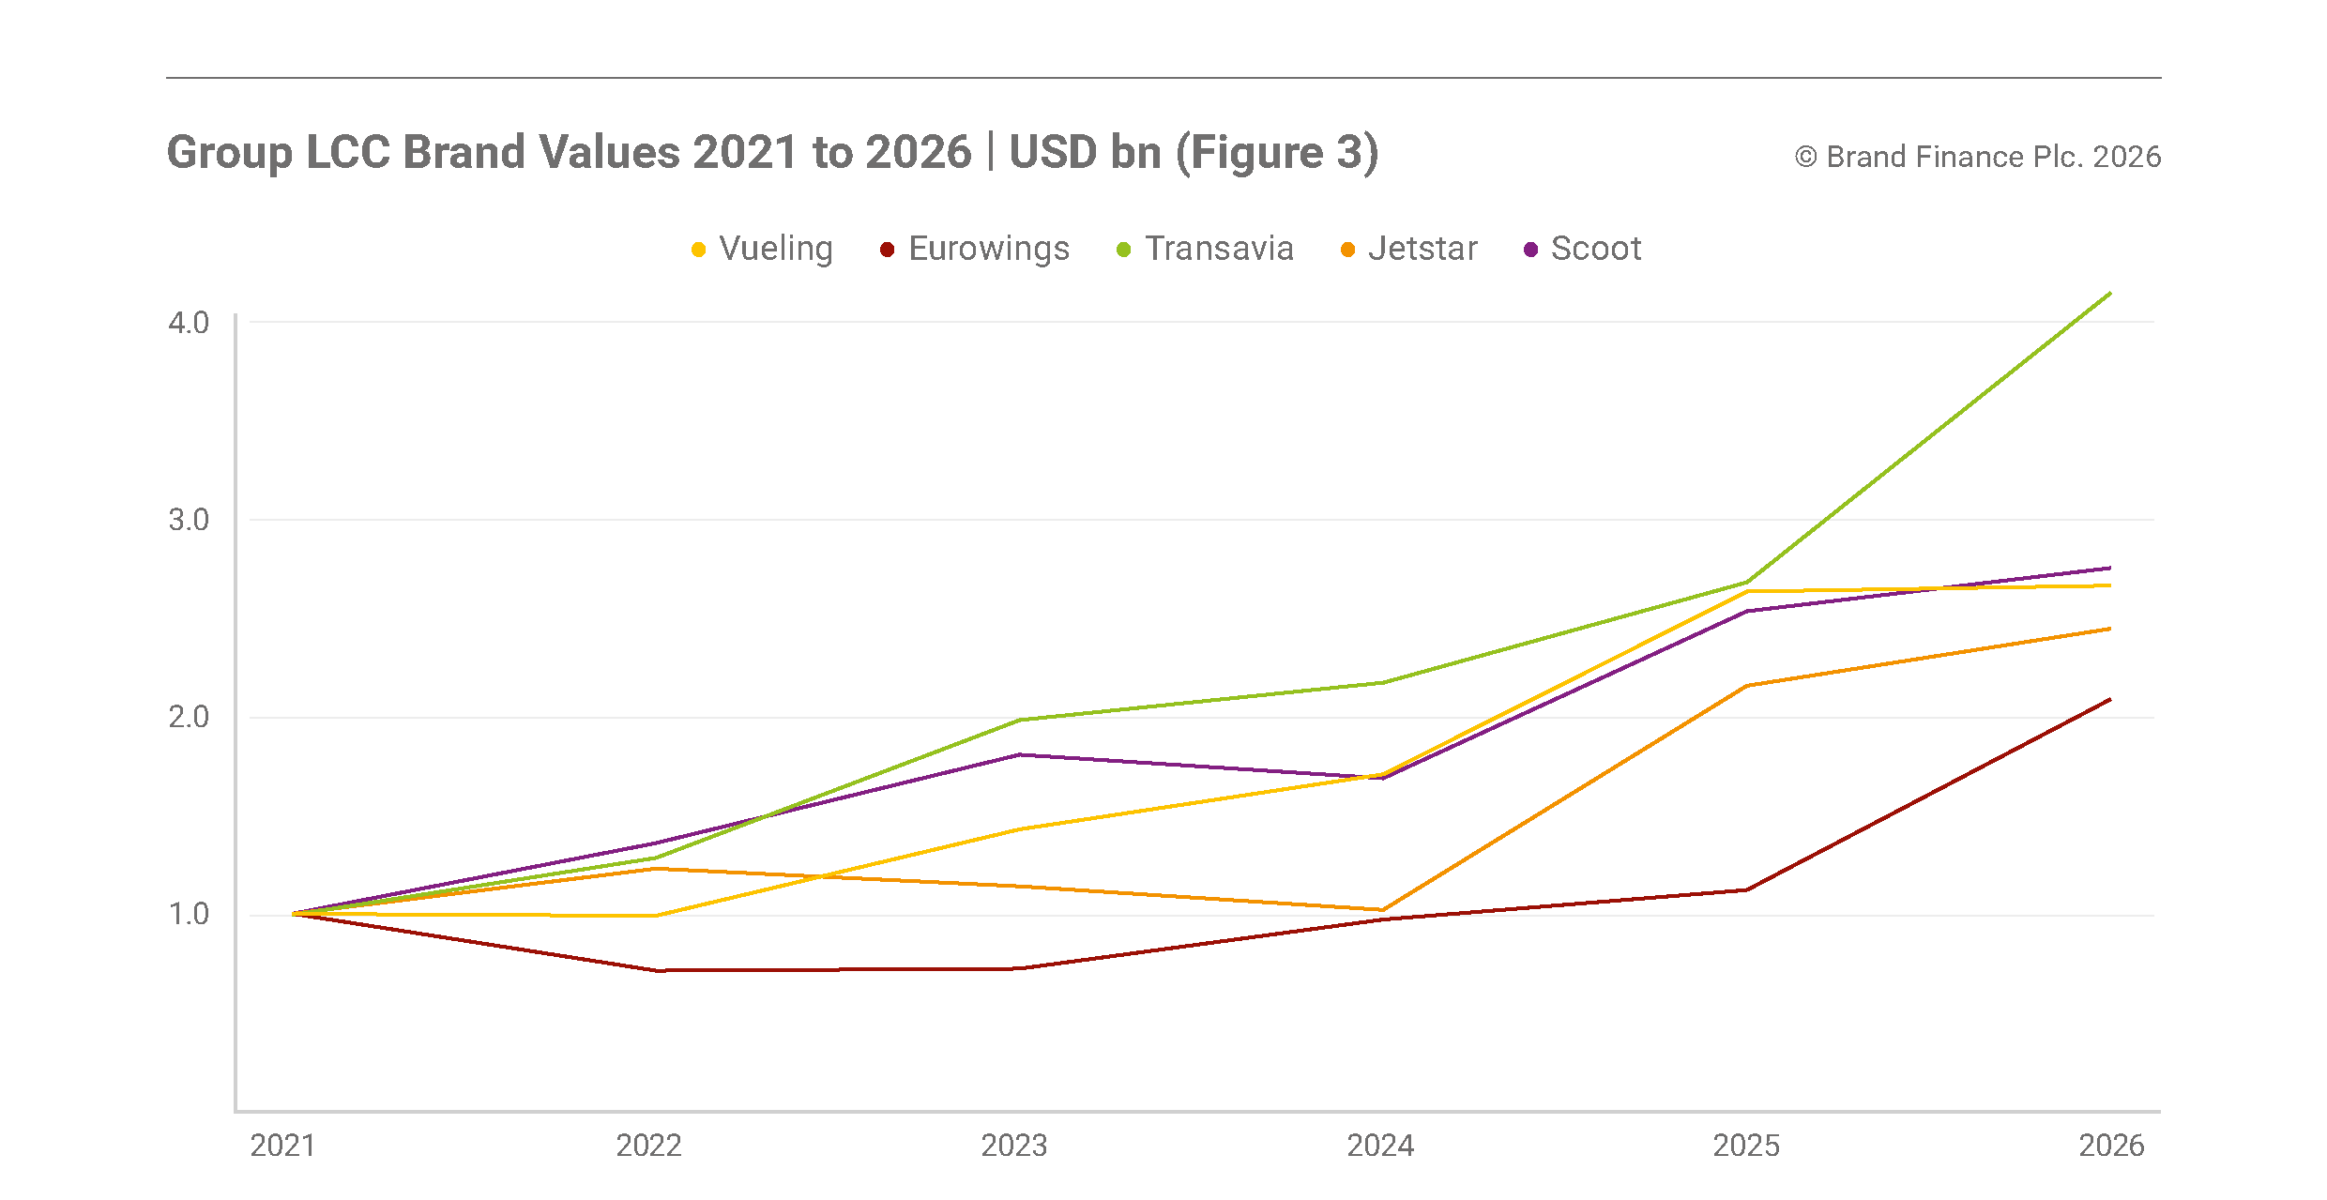
The most significant shift, however, is unfolding within legacy airline groups. Across major aviation portfolios, LCC subsidiaries are no longer simply complementary offerings, they are increasingly the engines of brand value growth. Eurowings recorded an 87% year on year increase in brand value. Transavia has quadrupled in value since its first Brand Finance rating in 2021 and now accounts for approximately 10% of total group brand value within Air France–KLM. Jetstar continues to scale steadily, posting 13% growth in 2026 and increasing its share of the Qantas Group brand value. Vueling has stabilised following a strong recovery from its 2021 trough, while Scoot, despite 14 years of operation, has yet to materially shift the concentration of value within the Singapore Airlines Group.
Structural drivers behind LCC outperformance
This outperformance reflects deeper structural shifts in the aviation market. The post pandemic recovery has been heavily leisure led, directly benefiting LCC brands that are optimised for short haul, price sensitive travel. Demand patterns have shifted away from corporate travel and towards discretionary travel, where affordability and flexibility are key.
At the same time, LCCs have been able to expand faster. Their lean operating models have enabled quicker network and capacity additions between 2023 and 2025, while many full-service carriers have faced constraints from aircraft delivery delays, labour shortages, and operational complexity.
Digital capability has also become a key differentiator. LCCs have strengthened their direct-to-consumer platforms, improving both margins and customer engagement. This has allowed them to build stronger brand relationships while maintaining cost efficiency, a combination that is increasingly difficult for traditional carriers to replicate.
A strategic infection points for airline groups
The implications for legacy airline groups are becoming increasingly difficult to ignore. The LCC tier is no longer a secondary brand within a portfolio, it is now a primary growth engine. Yet many airline groups continue to allocate brand investment, innovation, and customer experience enhancements disproportionately toward flagship carriers.
This imbalance is becoming a strategic risk.
The data shows clearly that LCC subsidiaries are outpacing their parent brands in growth, relevance, and increasingly, contribution to total group brand value. Brands such as Eurowings, Transavia, and Jetstar are no longer peripheral offerings. They are capturing the strongest demand tailwinds in the market and building meaningful brand equity in their own right.
For legacy groups, this requires a fundamental shift in mindset. LCC brands should no longer be positioned purely as cost-efficient alternatives, but as strategic growth platforms. This means elevating them within the brand architecture, strengthening their distinct positioning, and investing more deliberately in customer experience, digital ecosystems, and brand building.
Crucially, brand investment must follow growth. As leisure demand continues to dominate and price sensitivity remains high, the brands that are closest to this demand will shape future market leadership. Legacy carriers that continue to prioritise flagship prestige over LCC scalability risk misaligning with where value is actually being created.
From budget to mainstream brands
For standalone LCCs, the narrative is also shifting. Scale and brand strength are beginning to converge. With Ryanair at USD3.4 billion and IndiGo at USD1.7 billion, these brands are no longer defined purely by affordability. They are increasingly mainstream aviation brands, competing on reliability, reach, and customer experience.
The next phase of competition will depend on whether these brands can sustain and strengthen their Brand Strength Index scores alongside their expanding scale. Growth in brand value alone is no longer enough. Long term resilience will depend on maintaining trust, consistency, and relevance across increasingly diverse customer segments. The shift is clear. Low-cost carriers are no longer an alternative. For legacy airline groups, they are now a centre of gravity.